Fixing KYC Verification Failed Errors on Binance, Bybit, and OKX
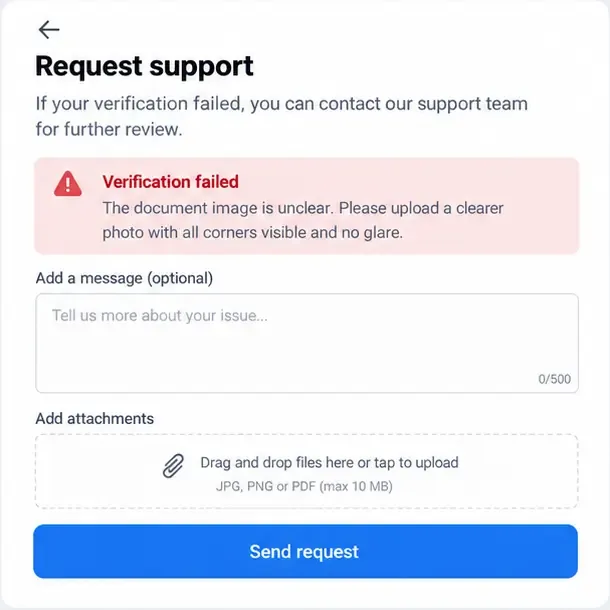
Learn how to fix KYC verification failures on Binance, Bybit, and OKX by correcting document, selfie, data mismatch, and account issues.
If you trade a currency pair whose quote currency differs from your account currency, the familiar “$10 per pip” shortcut may not apply. The reliable method is to calculate the pip value in the pair’s quote currency first, then convert that amount into your account currency using the correctly oriented exchange rate. This gives you a practical estimate of how much one pip is worth in your account before spread, commission, financing, or broker-specific conversion adjustments.
The examples below use hypothetical exchange rates for arithmetic practice, not live quotes. Rates and conversion methods vary by broker and can change while a position is open.
A currency pair has two currencies. In EUR/GBP, EUR is the base currency and GBP is the quote currency: the rate tells you how many pounds are needed for one euro. The quote currency is also the currency in which a price move creates the initial trading profit or loss. The CME Group’s explanation of FX quote conventions describes this base/quote relationship.
Your goal is to express the cash impact of a one-pip price move in your account’s home currency. If your account is in USD but the pair is EUR/GBP, the first calculation produces a GBP amount. A second conversion is needed to express that amount in USD. If the quote currency already matches the account currency, the conversion step is effectively a rate of 1.
For many retail spot FX pairs, one pip is 0.0001. For many pairs that include Japanese yen, one pip is 0.01. Some platforms also show a smaller fractional increment called a pipette—for example, a fifth decimal place on many non-JPY pairs or a third decimal place on some JPY pairs. A pipette is one-tenth of a pip in those common quote formats, but the instrument’s own specification should control. OANDA’s current web-platform guide describes these decimal conventions and notes examples such as JPY, THB, and HUF pairs. Check the contract or instrument details at your broker rather than assuming every FX product uses the same convention.
Use position size in base-currency units, not an unexplained lot label. A standard lot is often treated as 100,000 units in retail examples, but lot definitions, minimum trade sizes, and product specifications can differ. If your platform lets you enter units directly, use that number. If it shows lots, confirm the contract size and convert the lot amount into units first.
The core formula for a spot FX position quoted in units is:
Pip value in quote currency = position size in base-currency units × pip size
The units cancel in a useful way. For a 100,000-unit EUR/GBP position, each pip is a price change of 0.0001 GBP per EUR. Multiplying 100,000 EUR by 0.0001 GBP/EUR gives £10 per pip. This is the value before converting pounds into a different account currency.
For a JPY-quoted example, a 100,000-unit USD/JPY position and a 0.01 JPY pip size produce 1,000 JPY per pip: 100,000 × 0.01 = 1,000. Do not substitute 0.0001 in a JPY pair merely because that is familiar from EUR/USD.
Write the conversion rate with its units before doing the arithmetic. This prevents the most common error: multiplying when you should divide.
| Conversion quote | What the rate means | How to convert a quote-currency pip value |
|---|---|---|
| Quote currency / account currency (Q/A) | Account-currency units per 1 quote-currency unit | Multiply by the rate |
| Account currency / quote currency (A/Q) | Quote-currency units per 1 account-currency unit | Divide by the rate |
This is a dimensional check. If the rate is USD per GBP, multiplying a GBP amount by that rate cancels GBP and leaves USD. If the rate is JPY per USD, dividing a JPY amount by that rate cancels JPY and leaves USD.
Assume a 100,000-unit EUR/GBP position, a pip size of 0.0001, and a hypothetical GBP/USD rate of 1.2700. The first stage is:
A 25-pip favorable move would therefore represent about $317.50 before costs, assuming that conversion rate stays at 1.2700 for the calculation. A 25-pip adverse move has the opposite sign. This is an estimate of the price-move component, not a guaranteed account result.
Assume a 100,000-unit USD/JPY position, a 0.01 pip size, and a hypothetical USD/JPY conversion rate of 150.00. The quote-currency value is 100,000 × 0.01 = ¥1,000 per pip. Here, the conversion quote is JPY per USD: one dollar buys 150 yen. Divide to convert back to dollars:
Multiplying ¥1,000 by 150 would produce 150,000 yen, which moves the result farther from USD rather than converting it. When unsure, label the rate’s units and check which currency cancels.
Use the estimate as a check, then compare it with the platform’s displayed pip value, account-currency P/L, or trade calculator if available. Confirm that the platform is using the same position size, pip definition, account currency, and conversion rate. OANDA’s account-statement documentation, for example, shows unrealized P/L as price difference × position size × quote-to-home conversion rate and identifies the conversion rate used. That is useful evidence for the conversion step, but other brokers can apply their own methods.
The exchange rate used to convert realized or unrealized P/L may differ from the example’s mid-market rate. It can depend on the broker’s prevailing bid/ask or conversion rate, the time the conversion is applied, account settings, and any conversion markup or fee. OANDA’s U.S. charges page describes its own home-currency conversion treatment; do not assume its fee or timing applies to another provider. Read your broker’s fee schedule and account statement, especially if the displayed estimate and posted P/L differ by a small amount.
Once you have an account-currency pip value, multiply it by the planned stop distance to estimate the price-move exposure:
Estimated price-move amount = stop distance in pips × account-currency pip value
For the EUR/GBP example above, a 25-pip stop and an estimated $12.70 per pip imply $317.50 of price movement at the assumed conversion rate. That figure does not include spread, commission, slippage, gaps, financing, or changing conversion rates. It is not the same as a complete forecast of realized loss, and it does not establish that the position size is suitable for an account.
If those steps produce the expected currency units and a result close to the broker’s display, the arithmetic is internally consistent. A small difference may reflect rate timing or broker costs; a large difference usually calls for checking the pair’s pip size, contract size, or conversion direction again. The calculation is a planning aid, not a promise of a particular fill or outcome.
Learn how to fix KYC verification failures on Binance, Bybit, and OKX by correcting document, selfie, data mismatch, and account issues.
Learn how spot trading and margin trading differ in crypto, including ownership, leverage, liquidation risk, costs, order types, and beginner risk checks.
Learn how honeypot crypto scams block token sales, how to check sell simulations, taxes, liquidity, and contract controls before risking funds.
Learn how pump-and-dump schemes work, the warning signs to watch for, and practical steps to protect your capital from manipulated stocks and crypto assets.
Learn how to recover a locked crypto exchange account safely, prepare verification documents, complete security checks, avoid scams, and handle review delays.
Learn how Binance Dual Investment works, including Buy Low, Sell High, settlement, APR, liquidity limits, market risk, and Auto-Compound.
Learn why Binance withdrawals may be suspended, how to identify account or network restrictions, and the safest steps to restore access or retry.
Learn how crypto exchange Convert tools work, when a swap is truly zero-fee, how to compare quotes and spreads, and how to complete a conversion safely.
Missing a crypto deposit on Coinbase or Binance? Check confirmations, network, address, memo or tag, and the correct recovery path.
Learn how to calculate crypto risk-to-reward ratios, size positions, account for fees and slippage, and use R-multiples to manage trades consistently.