Home
» Knowledge
»
Options Implied Volatility vs. Historical Volatility: A Practical Comparison
Options Implied Volatility vs. Historical Volatility: A Practical Comparison
Illustrative scenario: Maya is considering a 30-day at-the-money call on a fictional stock, Northstar Tools, ahead of its scheduled earnings announcement. The stock is at $100. The option’s implied volatility is 40%, while the stock’s trailing 30-day historical volatility is 25%. Those percentages answer different questions. Historical volatility describes how much the stock moved over a past period. Implied volatility is derived from the price of the option and reflects the volatility level embedded in the market price for the option’s remaining life.
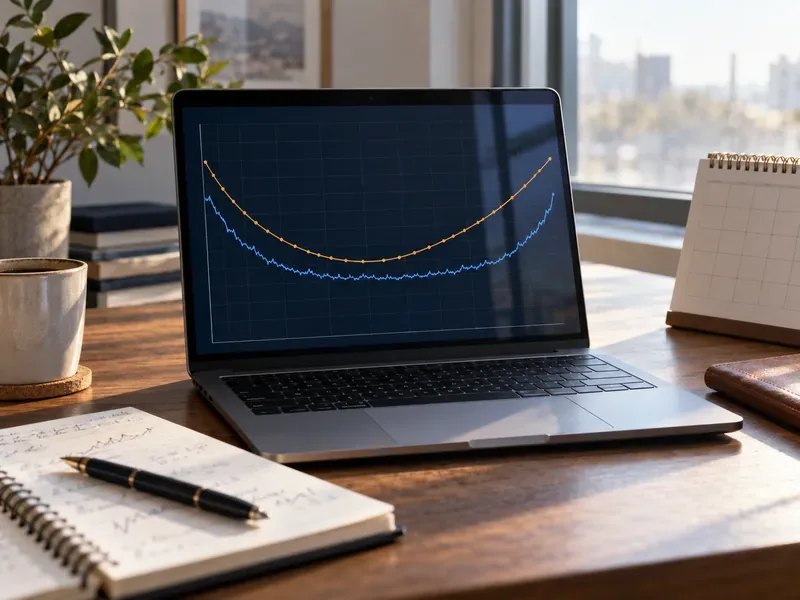
Two curves on a laptop illustrate that options can have different implied volatility levels across strikes, while a calendar highlights why the time period being compared matters.
The practical goal is not to decide that one number is “right.” Maya needs to know whether the comparison is matched well enough to inform her decision, what the IV-HV gap may represent, and what the numbers leave out. The gap can be a useful starting point for analyzing option pricing, but it is not by itself a trading signal or a forecast of what will happen next.
What each volatility measure tells you
Historical volatility (HV), also called realized volatility when measured over an observed period, is calculated from past changes in the underlying price. The result depends on the chosen lookback window, price sampling, and annualization convention. A 20-day HV and a 90-day HV can differ because they summarize different histories. HV is descriptive: it does not automatically predict the next period.
Implied volatility (IV) is obtained by taking an option’s market price and solving an option-pricing model for the volatility input that would produce that price, with other assumptions held in the model. IV is forward-looking in the sense that it refers to the option’s remaining life and is set through current option-market prices. It is not a direct observation of future volatility, nor a promise about the size or direction of the next move. The Options Industry Council explains both measures and distinguishes observed historical movement from volatility implied by current option prices.
Question
Historical volatility
Implied volatility
Where does it come from?
Past price changes in the underlying
Current option prices interpreted through a model
Which period does it describe?
A selected lookback window
The option’s remaining life, as reflected in its price
What can it help with?
Summarizing how turbulent the selected past was
Comparing the price of options across time, strikes, or markets
What can it not establish alone?
What volatility will be next
What volatility will actually be realized
Apply the comparison to Maya’s example
Maya sees 40% IV on the 30-day option and 25% trailing 30-day HV. The 15-percentage-point difference tells her the option’s model-implied volatility level is above the stock’s recent realized volatility. It does not prove that the option is overpriced. The stock’s next 30 days may be more volatile than the last 30 days, particularly because the option spans earnings. The market may also be pricing uncertainty that never appears in the eventual price path.
A rough way to put annualized volatility into a 30-day scale is to multiply it by the square root of the fraction of a year. Using 365 days for this illustrative calendar-day calculation:
At a $100 stock price, those correspond to rough one-standard-deviation move scales of about $11.50 and $7.20, respectively. These figures help Maya see the size of the difference in the same time units. They are not guaranteed ranges, target prices, or probabilities of profit. They rely on a simplified scaling convention and do not model jumps, volatility clustering, skew, dividends, or the specific effect of the earnings event.
She should also compare like with like: the same underlying, a similar horizon, and a clearly identified option. The IV of a 30-day at-the-money call is not directly interchangeable with the IV of a 90-day put far below the stock price. Different strikes and expirations can have different implied volatilities because the options market prices a volatility surface, not one universal number. The Chicago Mercantile Exchange describes how implied volatility is derived from option prices and notes that strike and call-put skew can change the levels observed across options.
Why a high IV-HV gap can mislead
The lookback may not match the forecast horizon
If Maya compares 30-day IV with one-year HV, she is putting a short option horizon beside a much longer record. If she uses 10-day HV, a brief quiet spell may make the gap look unusually wide. She should write down both windows and, where possible, review more than one trailing period. A comparison is more informative when the realized-volatility window is close to the option’s days to expiration, while still recognizing that the historical window is backward-looking.
An event can lift option prices
The fictional earnings announcement falls inside Maya’s option life. Traders may demand more premium for options that cover a scheduled event because the price could gap when new information arrives. That can raise IV even if recent daily moves were modest. If the event passes and the stock does not move enough to sustain the prior premium, IV can decline. This “volatility crush” is a possible outcome, not an automatic rule: the stock’s move, remaining time, supply and demand, and broader volatility conditions all matter.
IV is specific to strike and expiration
Put options can carry different IV from calls at the same expiration, and options at different strikes can carry different IVs. This skew can reflect demand for particular outcomes and structural features of the market. A broad index volatility measure such as the Cboe VIX is also not the same as a single-stock option’s IV. Cboe defines VIX as a measure of expected volatility over the next 30 days implied by SPX option quotations. Maya should compare Northstar’s option with Northstar’s own options and use VIX only as broad market context.
Option price is more than volatility
Even when IV changes, option value also responds to the underlying price, time remaining, interest rates, dividends where applicable, and the option’s Greeks. Bid-ask spreads and liquidity affect the price Maya can actually trade. A wide spread can make a displayed IV based on a midpoint less actionable. Before treating a gap as meaningful, check the bid and ask, recent trading activity, and whether the IV source uses a current, tradable quote.
A practical decision process
Choose the exact contract. Record the underlying, call or put, strike, expiration, and quote time. Use the same option throughout the comparison.
Match the horizon. Note the days remaining to expiration and compare it with one or more trailing realized-volatility windows near that length. Keep the annualization basis consistent.
Check the option surface. Compare IV with nearby strikes and expirations. A single contract can be high relative to the underlying’s recent history but ordinary relative to other options covering the same event.
Identify known events. Earnings, product announcements, regulatory dates, and macro releases may affect the option’s premium. Confirm dates from the company or relevant authority rather than assuming a calendar listing is current.
Translate IV to a move scale. Use a clearly labeled approximation such as annualized IV × √(days/365), and treat the output as a model-based scale, not a forecast.
Stress-test the trade. Consider what happens if the underlying moves, time passes, or IV falls after the event. A long option can lose value even if the underlying moves in the expected direction when the move is too small or occurs too slowly; a short option can face losses from a sharp move or volatility increase.
For Maya, this process might lead her to wait until after earnings, choose an expiration that does not include the event, use a spread to define some risk and premium exposure, or decide the uncertainty is not worth trading. The right response depends on her objective and risk limits, not on the 15-point difference alone.
How to tell whether the comparison is useful
A useful IV-versus-HV comparison has three visible qualities: the same underlying is being measured; the option’s strike and expiration are known; and both volatility figures have stated time windows and annualization conventions. The result should help explain what is embedded in the option premium and what historical behavior it is being compared with.
Change the comparison if the IV quote is stale or the spread is wide, if the contract covers a major event absent from the historical window, or if the two volatility windows are materially different. Add context from the term structure, skew, and the underlying’s event calendar. If the contract is thinly traded or pricing inputs are unclear, treat the displayed IV as an estimate with limited precision.
Neither number removes uncertainty. HV can change sharply when the lookback window rolls forward; IV can move with market demand and option prices. The gap between implied and subsequently realized volatility is sometimes called a volatility risk premium, but its size and sign vary by market, period, and option selection. Cboe notes that SPX implied volatility has tended over long periods to exceed subsequent realized volatility; that observation does not guarantee the same relationship for an individual stock, a particular expiration, or a specific trade.
Volatility is a measurement framework, not a complete forecast. In Maya’s hypothetical case, the 40% IV and 25% HV help frame what the option price is implying relative to recent history. The next useful step is to verify the contract, compare matching horizons, account for the earnings date, and decide whether the premium and possible outcomes fit her plan.