Home
» Knowledge
»
Risk of Ruin for Traders: A Simple Calculation Using Win Rate and Payoff Ratio
Risk of Ruin for Traders: A Simple Calculation Using Win Rate and Payoff Ratio
Risk of ruin is not a prediction of whether your next trade will win. It is an estimate of how likely a trading process is to hit a predefined failure threshold after a sequence of wins and losses. The useful outcome is not a single dramatic percentage; it is a repeatable way to test whether your win rate, payoff ratio, and position size leave enough room for normal losing streaks.
A simple risk-of-ruin check starts with measurable inputs: win rate, average payoff, risk per trade, and a clearly defined loss threshold.
What you should be able to calculate
At minimum, you should be able to answer four questions from your own trade history:
What percentage of trades are winners?
How large is the average winner relative to the average loser?
How much capital is actually at risk on one trade?
What drawdown would force you to stop, reduce size, or rebuild the strategy?
Those inputs are more useful than win rate alone. A system can win less than half the time and still have positive expectancy if the average winner is large enough. Conversely, a high win rate can still produce poor results when losses are much larger than wins.
Start with expectancy, not ruin
Let p be the win rate, q = 1 - p the loss rate, and b the payoff ratio, defined as average win divided by average loss. If one average loss is treated as 1R, then the expected result per trade is:
Expectancy = p × b - q
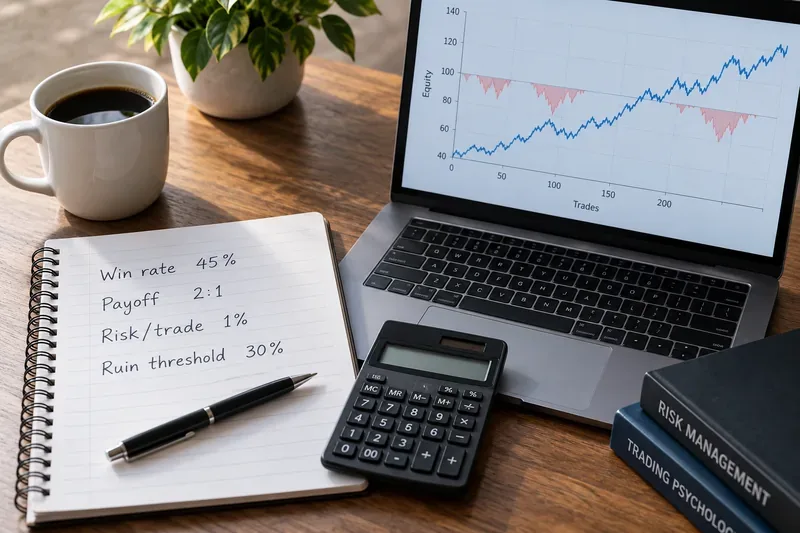
For example, a 45% win rate with a 2:1 payoff ratio gives:
0.45 × 2 - 0.55 = +0.35R per trade
That is a positive mathematical edge under the simplified assumptions. The break-even win rate is:
Break-even win rate = 1 / (1 + b)
At a 2:1 payoff ratio, the break-even rate is 33.3%. At 1:1, it is 50%. At 0.5:1, it is 66.7%. This relationship is arithmetic, not a forecast: commissions, spread, slippage, taxes, partial exits, gaps, and changing market conditions can lower realized expectancy.
The exact simple formula works cleanly for 1:1 outcomes
The classic gambler’s-ruin model treats capital as a random walk that rises one unit after a win and falls one unit after a loss. University probability notes from MIT and Stanford present this framework and its boundary-hitting probabilities.
If each win earns exactly 1R, each loss costs exactly 1R, the win probability is p, and the account begins N loss-units above the ruin point, then for p > 0.5 the infinite-horizon probability of eventually hitting ruin is:
Risk of ruin = (q / p)N
If p is 0.55, q is 0.45, and the trader can absorb 20 fixed 1R losses before reaching the ruin threshold, the model gives:
(0.45 / 0.55)20 ≈ 1.81%
If p is 0.50 or lower in this equal-payoff, infinite-horizon model, eventual ruin probability is 100%. That result is often misunderstood. It does not mean a trader must immediately lose everything; it means that if a nonpositive-edge process continues forever with a fixed loss boundary, the probability of eventually touching that boundary approaches one.
Why payoff ratios above or below 1:1 need more care
Once wins and losses have different sizes, the one-step random walk is no longer “up 1, down 1.” A 45% win rate with a 2R winner and a 1R loser moves in uneven jumps. Plugging the payoff ratio into the 1:1 gambler’s-ruin formula as if nothing changed can give a false sense of precision.
A useful approximation for a binary system with outcomes of +bR and -1R starts with the mean and variance of one trade:
μ = p × b - q
σ² = p × b² + q - μ²
For a positive-edge process, a diffusion-style approximation for reaching a lower boundary U risk units away is:
Risk of ruin ≈ exp(-2 × μ × U / σ²)
This form is related to first-passage results for Brownian motion with drift. MIT’s Advanced Stochastic Processes lecture notes cover Brownian motion with drift and hitting-time methods. Treat this trading use as an approximation, not an exact closed form for every strategy.
A worked example: 45% wins, 2:1 payoff
Suppose a strategy has a 45% win rate, an average winner of 2R, and an average loser of 1R. You define “ruin” as a 30% drawdown from starting capital. For illustration, assume a fixed-dollar risk unit equal to 1% of starting capital, so the ruin boundary is 30R away.
The expectancy is μ = 0.35R. The variance is:
σ² = 0.45 × 2² + 0.55 - 0.35² = 2.2275
The approximate risk of reaching the 30R lower boundary is:
exp(-2 × 0.35 × 30 / 2.2275) ≈ 0.008%
That number is small under the model, but its main value is comparative. Keep the same win rate and payoff ratio and change only position size: with a 30% ruin threshold, risking 2% of starting capital per trade leaves 15 risk units and raises the approximation to about 0.90%; 3% leaves 10 units and gives about 4.32%; 5% leaves only 6 units and gives about 15.17%.
Risk per trade
Risk units to 30% drawdown
Approx. ruin risk
0.5%
60
~0.00000065%
1%
30
~0.008%
2%
15
~0.90%
3%
10
~4.32%
5%
6
~15.17%
The lesson is not that one of these percentages is “safe” for everyone. It is that position size changes survival odds even when the strategy statistics do not change.
How to judge whether the result is good enough
A useful risk-of-ruin calculation should pass three quality checks.
1. The inputs come from enough trades to be credible
A win rate from 20 trades can move sharply after only a few new outcomes. Payoff ratio can be even noisier if a small number of large winners dominate the average. Recalculate with rolling samples and separate live results from backtests. If the estimate changes dramatically whenever a few trades are added or removed, the input statistics are not yet stable enough to support a confident ruin estimate.
2. The ruin threshold matches a real decision
“Ruin” does not have to mean a zero balance. A more operational threshold might be the maximum permitted account drawdown, a prop-account loss limit, or the point where you would suspend the strategy. The model becomes more useful when the boundary corresponds to an action you would genuinely take.
3. The position-size assumption matches execution
Fixed-dollar risk and fixed-fractional risk behave differently. Under fixed-fractional sizing, the dollar amount at risk shrinks after losses, which slows account decay. CME Group’s risk-management material illustrates this effect and emphasizes defining both a stop and a percentage or dollar amount at risk before placing a trade. See CME Group’s position-sizing lesson and its comparison of 1% and 2% risk during losing streaks.
When the simple model should be replaced
Switch to Monte Carlo or a strategy-specific path model when any of these conditions matter:
Wins and losses have a wide distribution instead of two fixed outcomes.
Trades are correlated, clustered by regime, or exposed to the same market factor.
Position size changes dynamically.
Stops can gap, slip, or fail to limit losses to the planned 1R.
There are partial exits, scale-ins, pyramiding, or multiple simultaneous positions.
You care about a finite horizon such as the next 100 or 500 trades rather than an infinite sequence.
Monte Carlo simulation can preserve your actual trade-return distribution, shuffle or resample paths, and estimate how often a chosen drawdown threshold is crossed. It still depends on assumptions: if the future distribution differs from the sample, the result can be wrong.
Leverage can invalidate a tidy calculation
A spreadsheet may assume the largest loss is exactly 1R. Real leveraged trading can break that assumption during gaps, fast markets, liquidation, or margin calls. The U.S. Securities and Exchange Commission notes that margin investors can lose more than the amount initially invested and may face forced sales. See the SEC’s margin-risk guidance. If one loss can materially exceed your planned stop, use the realized loss distribution rather than the nominal stop distance.
A practical decision rule
Use risk of ruin as a stress test, not as a badge of strategy quality. First confirm positive expectancy after realistic costs. Then calculate how many loss units sit between current equity and the failure threshold. Finally, test how the result changes when you reduce the assumed win rate, reduce the payoff ratio, and increase loss size.
A robust setup should not look acceptable only under one optimistic set of inputs. If a modest deterioration in win rate or payoff makes ruin risk jump sharply, the more useful response is usually to reduce position size, gather more evidence, or redesign the strategy before increasing exposure.
Bottom line
Win rate and payoff ratio tell you whether a simplified strategy has positive expectancy, but they do not determine risk of ruin by themselves. You also need position size and a clearly defined ruin threshold. For equal 1R wins and losses, the classic gambler’s-ruin formula is exact under its assumptions. For unequal payoffs, a diffusion approximation can provide a quick comparison, while Monte Carlo is better when trade outcomes, sizing, and market behavior are more realistic.
The best sign that the calculation is useful is not a tiny percentage on the screen. It is that your conclusion remains sensible after conservative changes to the assumptions—and that your planned risk per trade is small enough to survive the losing streaks your own data says can happen.