Home
» Knowledge
»
Theta Decay Over Weekends: When Options Models Price Non-Trading Days
Theta Decay Over Weekends: When Options Models Price Non-Trading Days
A common options-trading surprise arrives on Monday morning: an option does not open exactly where Friday’s displayed theta seemed to imply. A trader may see a theta of -0.10 on Friday and assume that a three-day weekend should automatically reduce the option’s value by about $0.30, all else equal. In practice, that shortcut can be misleading because different pricing systems measure time differently, implied volatility can adjust before the weekend, and Monday’s market can reopen with a changed underlying price or volatility surface.
The key question is not simply, “Does theta decay over the weekend?” It is: how does the model behind the number measure time, and how does the market incorporate non-trading periods into implied volatility? CME Group’s options education material explicitly warns users to check what unit of time their theta calculation references. Cboe LiveVol, for example, states that its implied-volatility calculations use calendar days, including partial days, while other analytics may use business-day or weighted-time conventions. See CME Group’s explanation of theta and Cboe LiveVol’s options analytics methodology.
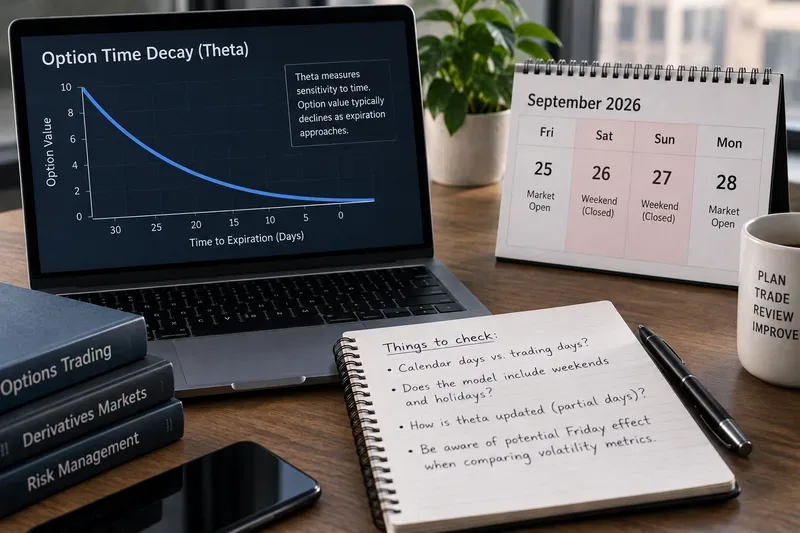
An options workspace comparing time decay with a Friday-to-Monday calendar interval. The practical issue is whether the model counts those non-trading days as full time, reduced time, or through another convention.
Does theta decay on Saturday and Sunday?
It can, depending on the model convention. In a calendar-day implementation, time to expiration decreases continuously even when the exchange is closed. A Friday close to Monday open therefore removes roughly three calendar days from time to expiration. In a trading-day model, the weekend may contribute little or no model time because the clock is defined mainly around trading sessions. Hybrid models can assign weekends a smaller weight than open-market hours rather than treating all hours equally.
This distinction matters because theta is not cash mechanically removed from an option account every midnight. Theta is a model sensitivity: it estimates how option value changes as time passes while the other model inputs are held constant. Real market prices do not hold those inputs constant.
Why can Monday’s price differ from Friday theta multiplied by three?
Several things can happen between Friday’s close and Monday’s open.
The underlying can gap. News, macro events, overseas trading, or company-specific developments can change the expected value of the underlying before the next regular session.
Implied volatility can change. Market makers can adjust volatility estimates before the weekend or when trading resumes. That change can offset or amplify time decay.
The model clock may not be a calendar clock. A displayed daily theta can be based on 365 days, approximately 252 trading days, or a proprietary weighted-time schedule.
Theta itself changes. It is generally not constant. CME notes that time decay tends to accelerate for at-the-money options as expiration approaches.
That is why “Friday theta × 3” should be treated as a rough thought experiment, not a forecast of Monday’s opening premium.
How do calendar-day models handle weekends?
A calendar-day model reduces time to expiration every hour, including nights, weekends, and holidays. Cboe LiveVol states that it uses calendar days, including partial days, as the time-to-expiration input for implied-volatility calculations and that its analytics track intraday decay.
Suppose an option has 10.0 calendar days remaining at Friday’s close. By Monday at the same clock time, a calendar-day model would have about 7.0 days left, assuming no intervening expiration rule or holiday nuance. If the underlying price, interest rate, dividends, and implied volatility were frozen, the model would generally produce a lower time value simply because there is less remaining time.
But the market is not frozen. A calendar-day model often requires implied volatility to absorb differences between quiet non-trading periods and more active trading hours. Cboe has documented a related “Friday effect” in volatility calculations: moving between business-day and calendar-day conventions can create visible Friday/Monday patterns because market makers adjust quotes to account for the weekend. See Cboe’s Implied Correlation methodology discussion of trading versus calendar days.
What changes in a trading-day model?
A trading-day model effectively concentrates more of the annual variance budget into sessions when the market is open. Instead of counting 365 equally weighted days, it may use roughly the number of business or exchange-trading days in a year. In a simplified version, Saturday and Sunday contribute no model time at all.
That does not mean weekend risk disappears. Information still arrives when the regular market is closed, and Monday can open at a materially different underlying price. The model simply allocates the passage of variance differently.
This is why two platforms can display different theta values for the same option even when they agree closely on fair value. If one divides annualized decay across calendar days and another across trading days, the daily figure can differ because the denominator differs.
Are holidays treated the same way as ordinary weekends?
Not necessarily. Exchange calendars can have full closures, early closes, overnight sessions, or product-specific schedules. In 2026, Cboe continues to distinguish calendar date, business date, and trade date in its options-market documentation, and some products operate outside standard regular trading hours. That makes a blanket rule such as “every closed day equals one full theta day” unreliable.
For any option close to expiration, verify the actual trading and expiration schedule of the product rather than assuming a standard Monday-through-Friday pattern. Cboe publishes current hours and holiday information through its exchange resources, including its hours and holidays pages.
Which questions should you answer before holding an option through a weekend?
Question
Why it matters
What to check
What time convention does my platform use?
It determines how the displayed theta maps to calendar time.
Broker documentation, analytics methodology, model settings.
Is theta shown per calendar day or trading day?
The same annualized model can produce different “daily” theta numbers.
Greek definitions and annualization convention.
How close is expiration?
Short-dated options are more sensitive to both time passage and volatility changes.
Exact expiration date and settlement rules.
Is an event scheduled during the closed period?
Weekend news risk can outweigh expected time decay.
Friday volatility surface, event premium, Monday opening IV.
Is there a “free theta” trade from selling options before the weekend?
No reliable free-theta rule follows from the calendar alone. If the market expected a predictable three-day decay that sellers could capture without corresponding risk, that expectation would tend to be incorporated into Friday’s option prices and implied volatility. The premium a seller receives compensates for uncertainty during a period when normal trading may be unavailable or limited.
This is especially important for short-dated options. A seller may benefit from time decay if the underlying and implied volatility remain favorable, but a Monday gap can produce losses much larger than the theta collected. The absence of regular trading does not mean the absence of economic risk.
When does weekend theta matter most?
The effect deserves the most attention when expiration is near, the option is near the money, or an event can occur while the market is closed. Near expiration, a small change in time remaining can have a large effect on time value. CME’s theta material notes that at-the-money time decay typically becomes more pronounced as expiration approaches.
Far-dated options are usually less sensitive to a single weekend in percentage terms because the removed time is a much smaller share of total time to expiration. That does not make the convention irrelevant, but the practical price difference is usually less dominant than it is for options with only a few days left.
How can you test what your own platform is doing?
You do not need to guess. Use a simple before-and-after check over several ordinary weekends.
Record Friday’s option price, underlying price, implied volatility, theta, and exact time to expiration.
Record the same fields at Monday’s open or at the first comparable timestamp.
Separate the contribution of the underlying move from the volatility move. Do not attribute the full price change to theta.
Read the platform’s Greek methodology and note whether it uses calendar days, business days, partial days, or another convention.
Repeat across multiple weekends, including one farther from expiration and one closer to expiration.
If the platform explicitly uses calendar days, you should expect model time to pass over the weekend. If it uses trading days, the displayed daily theta may be larger on open-market days because the annual decay is spread across fewer modeled days. If the methodology is undisclosed, treat the displayed Greek as platform-specific rather than universally comparable.
A simple way to interpret weekend theta
Think of theta as a model estimate under a stated clock, not as a scheduled debit or credit. Weekend and holiday periods matter because time to expiration changes, but the size and timing of the modeled decay depend on how that clock is defined. The observed Monday price also reflects everything that changed while the market was closed.
Before making a weekend options decision, verify three things: the model’s time convention, the product’s actual trading and expiration schedule, and the event risk carried through the closed period. If those three are clear, the Friday-to-Monday price change becomes much easier to interpret without assuming that theta alone explains it.