Home
» News
»
October 2026 U.S. Treasury Auction Calendar: Dates That Could Move Yields and the Dollar
October 2026 U.S. Treasury Auction Calendar: Dates That Could Move Yields and the Dollar
October 2026 has several U.S. Treasury auction clusters that fixed-income and FX traders may want on their calendars, especially the October 6–8 3-year, 10-year and 30-year sales; the October 21–22 20-year bond and 5-year TIPS sales; and the October 26–29 2-year, 5-year, 2-year FRN and 7-year auctions. Those dates are confirmed on the Treasury Department's current tentative six-month auction schedule, but the word tentative matters: offering sizes and final terms come from the individual auction announcements, and scheduled dates can still change.
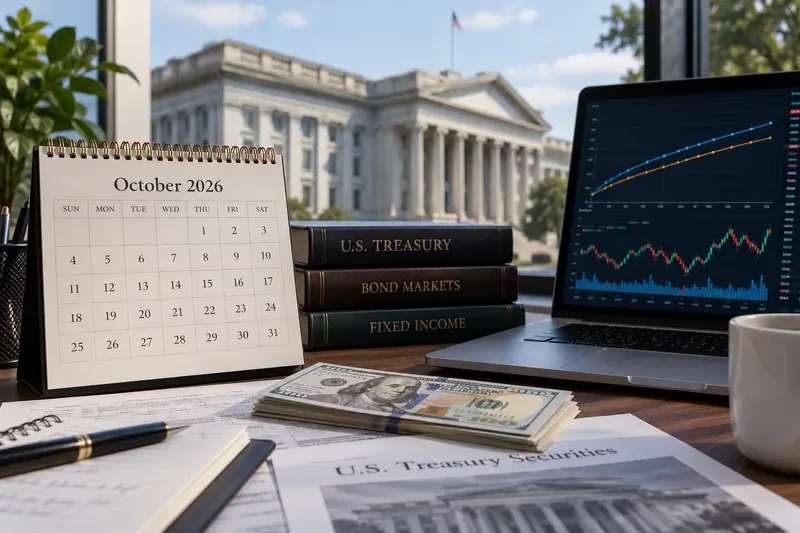
An October 2026 calendar beside bond-market materials illustrates why Treasury announcement and auction dates deserve a place on a rates and FX watchlist.
The October 2026 dates that deserve the most attention
The Treasury schedule separates three events that are often confused: the announcement date, the auction date and the settlement or issue date. Treasury explains that the announcement sets out the security, amount offered, auction date, issue date, maturity date, bidding deadlines and other terms. The actual auction then determines the accepted rate, yield or discount margin. See TreasuryDirect's How Auctions Work page for the official process.
For market prices, the auction date is usually the event to watch most closely because that is when demand is tested and the clearing level is determined. The announcement date can also matter if the amount offered or other terms differ from expectations. Settlement is operationally important, but it is not the same event as price discovery.
Action: Put both announcement and auction dates on your calendar, then replace tentative details with the final terms as soon as Treasury publishes the announcement.
Security
Announcement
Auction
Settlement
Why traders may watch it
3-year note
Oct. 1
Oct. 6
Oct. 15
Tests demand in the front-to-intermediate part of the curve.
10-year note reopening
Oct. 1
Oct. 7
Oct. 15
A benchmark maturity closely followed across global rates markets.
30-year bond reopening
Oct. 1
Oct. 8
Oct. 15
Tests long-duration demand and can affect the long end of the curve.
20-year bond reopening
Oct. 15
Oct. 21
Oct. 23
Can reveal demand conditions in a less liquid long-duration sector.
5-year TIPS
Oct. 15
Oct. 22
Oct. 30
Relevant to real yields and market-based inflation pricing.
2-year note
Oct. 22
Oct. 26
Nov. 2
Sensitive to the expected path of Federal Reserve policy.
5-year note
Oct. 22
Oct. 27
Nov. 2
Bridges the policy-sensitive front end and intermediate curve.
2-year FRN
Oct. 22
Oct. 28
Nov. 2
Useful for reading demand for floating-rate Treasury exposure.
7-year note
Oct. 22
Oct. 29
Nov. 2
Can influence the intermediate-to-long section of the curve.
Misconception: every Treasury auction moves the 10-year yield and the dollar
That is not supported by the auction calendar alone. Treasury also auctions bills every week, including 4-week, 6-week, 8-week, 13-week, 17-week, 26-week and, at intervals, 52-week bills. In October, bill auctions are scheduled on October 1, 5, 6, 7, 8, 13, 14, 15, 19, 20, 21, 22, 26, 27, 28 and 29, depending on maturity. These can matter greatly for money-market rates, liquidity and very short-dated Treasury pricing, but they do not automatically produce a large move in the 10-year yield or the dollar.
The market impact depends on context: the size being sold, dealer and investor demand, whether the result is stronger or weaker than expected, the macro backdrop and what other data or Federal Reserve communication hits at the same time.
Action: Treat bill auctions as front-end liquidity events first. Escalate them on your broader rates or FX watchlist when issuance size, funding conditions or demand becomes unusually important.
Misconception: the scheduled auction date tells you the final amount being sold
It does not. The six-month calendar provides the planned security type and dates, not the final offering amount for every future auction. Treasury says each individual announcement supplies the amount offered and the auction's detailed terms. As of September 29, 2026, later-October offering sizes should not be guessed if their announcements have not yet been released.
This distinction matters because supply surprises can change the amount of duration that investors must absorb. A larger-than-expected coupon offering can pressure yields higher before the auction if investors demand more concession; a smaller amount can have the opposite effect. But that relationship is conditional, not mechanical.
Action: On October 1, October 15 and October 22, check the official TreasuryDirect Auctions page for final announcements rather than relying on an old calendar screenshot.
How an auction can move Treasury yields
Treasury uses single-price auctions. According to the official auction FAQs, successful bidders receive the same price, based on the highest accepted rate, yield or discount margin among competitive tenders. TreasuryDirect also notes that competitive bidders specify the yield or rate they are willing to accept and that awards proceed from the lowest bids upward until the offering is filled.
For notes, bonds and TIPS, the result can affect secondary-market yields if the clearing yield reveals demand that is materially different from what traders expected immediately before the sale. A stronger result can support the issue and nearby maturities; a weaker result can push yields higher as the market reprices the level needed to attract buyers.
No single metric should be treated as a guaranteed signal. Traders often look at the auction's high yield relative to the pre-auction market level, bid-to-cover ratio and the distribution of awards among bidder categories, but interpretation depends on the security and market conditions.
Action: Compare the auction result with the prevailing secondary-market yield just before the close, rather than judging the result from an isolated statistic.
How the dollar can react — and why the direction is not automatic
The U.S. dollar can respond to Treasury auctions through interest-rate differentials and broader risk sentiment, but there is no fixed rule that a weak auction makes the dollar rise or fall. If an auction pushes U.S. yields higher relative to foreign yields, the dollar may receive support because dollar assets offer a higher yield. In another setting, a disorderly rise in long-term yields may be interpreted as a risk or fiscal-premium shock, producing a different FX response. The surrounding macro story matters.
That is why the 10-year and 30-year auctions on October 7 and 8, and the late-month 2-year through 7-year sequence on October 26–29, are useful cross-market checkpoints rather than standalone dollar forecasts.
Action: When a Treasury auction moves yields, check whether U.S.-foreign yield spreads are moving in the same direction before attributing a dollar move to the auction.
October 12 holiday: a small calendar detail that can cause confusion
The official Treasury schedule marks Monday, October 12, 2026 as Columbus Day. Around that holiday, several regular bill auctions shift from the usual rhythm: 6-week, 13-week and 26-week bills are scheduled for Tuesday, October 13 rather than Monday, and the next 17-week auction is Wednesday, October 14.
This is a scheduling adjustment, not evidence of unusual financing stress.
Action: If your usual Monday bill-auction alert shows nothing on October 12, check the holiday-adjusted Treasury schedule before assuming an auction was canceled.
Settlement dates matter, but they are not the result time
Auction and settlement dates are separated by days in many cases. The October 6–8 coupon auctions all settle on October 15. The October 26–29 2-year, 5-year, FRN and 7-year auctions settle on November 2. TreasuryDirect explains that the issue date is when awarded securities are delivered and payment is taken.
Settlement can affect dealer balance sheets, cash management and financing conditions, especially when large issues settle together. Still, if you are watching for the immediate price reaction to demand, the auction close and result are usually more relevant than settlement.
Action: Use auction dates for price-discovery alerts and settlement dates for funding and liquidity planning.
A practical October watchlist
October 1: Announcement day for the 3-year, 10-year and 30-year coupon cluster.
October 6–8: 3-year, 10-year and 30-year auctions — the month's first major coupon sequence.
October 15: Announcement day for the 20-year bond and 5-year TIPS.
October 21–22: 20-year bond and 5-year TIPS auctions.
October 22: Announcement day for the late-month 2-year, 5-year, 2-year FRN and 7-year sequence.
October 26–29: 2-year, 5-year, 2-year FRN and 7-year auctions.
The schedule is useful, but it is not a forecast. The verified fact is when Treasury currently plans to announce, auction and settle each security. What is still unknown before each announcement is the final offering amount and other terms. What remains conditional is the size and direction of any reaction in Treasury yields or the dollar.
Action: Use the official Treasury marketable securities page as the source of record and re-check the calendar on the morning of each key date.