Home
» News
»
Decentralized Stablecoins Compared: USDe, FRAX, and DAI Security Models
Decentralized Stablecoins Compared: USDe, FRAX, and DAI Security Models
“Decentralized stablecoin” is a useful category label, but it can hide radically different security assumptions. USDe, FRAX, and DAI do not protect a dollar-like value in the same way. A practical risk review therefore starts with a more specific question: what has to keep working for each token to remain solvent and near $1?
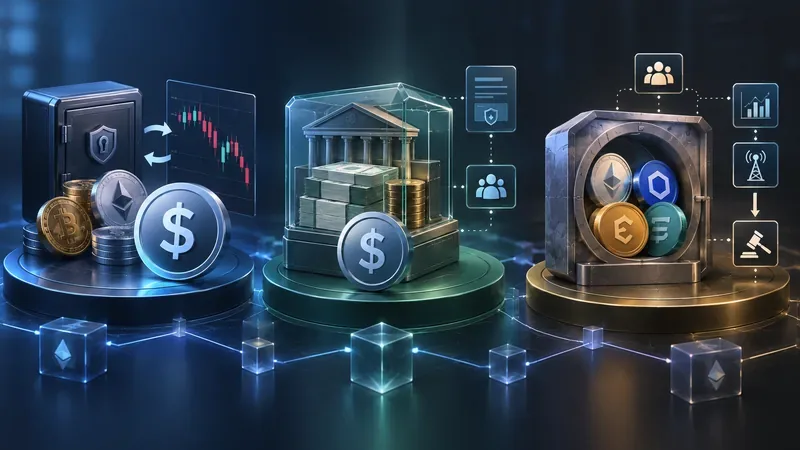
Three broad stablecoin security patterns: market-neutral hedging, reserve-backed issuance, and collateralized debt with liquidations.
This comparison reflects official documentation checked on September 15, 2026. One naming issue matters immediately: Frax’s current dollar stablecoin is frxUSD. Legacy FRAX documentation describes the earlier FRAX V3 model, while current Frax documentation describes frxUSD as fully collateralized by permitted cash-equivalent reserves such as tokenized U.S. Treasury funds. Treating “FRAX” as if its old design were unchanged would therefore give an outdated risk picture.
Quick comparison: what actually secures the dollar?
System
Primary security model
Peg/solvency machinery
Important trust dependencies
USDe (Ethena)
Crypto backing plus offsetting derivatives; liquid stable assets may also be held
Delta hedging, mint/redemption arbitrage, off-exchange settlement, reserve fund
Current frxUSD: 1:1 permitted cash-equivalent reserves, including tokenized Treasury funds. Legacy FRAX V3 targeted at least 100% collateralization and used AMOs.
Custodian mint/burn routes and reserve redemption; Frax ecosystem contracts and governance
Collateral quality, oracle operation, liquidation markets, governance, smart contracts and real-world/custodial exposures in the collateral portfolio
USDe: security through a hedged balance sheet
Ethena describes USDe as a synthetic dollar, not a conventional fiat stablecoin. Its core idea is to hold backing assets while taking offsetting short derivatives positions. If the protocol holds an asset with positive price exposure and shorts an equivalent amount of that exposure, gains on one side should offset losses on the other, producing a roughly delta-neutral portfolio. Ethena states that it uses BTC, ETH and other governance-approved assets, as well as liquid stablecoins, while derivatives include perpetual and deliverable futures.
That changes the threat model. USDe does not depend primarily on borrowers maintaining excess collateral in individual on-chain vaults. It depends on the combined spot-and-derivatives portfolio remaining properly hedged, accessible and solvent. Ethena’s own documentation explicitly says its design contains both on-chain and off-chain components. The protocol uses off-exchange settlement providers to custody backing while delegating assets to centralized exchanges for margin without transferring custody to those exchanges. Read Ethena’s USDe overview, delta-neutral stability explanation, and custody model.
What can fail?
The obvious risks are broader than “crypto prices fall.” A correctly matched hedge is intended to neutralize much of that directional exposure. More relevant failure paths include imperfect hedges, basis dislocations, backing-asset divergence, derivatives-exchange problems, custody or settlement failures, smart-contract exploits, and sustained adverse funding economics. Ethena maintains a reserve fund as an additional safety margin for negative funding periods and as a potential bidder for USDe in stressed markets. That is a buffer, not a guarantee against every loss scenario. See the official Reserve Fund documentation.
For a holder, another practical distinction is redemption access. Ethena’s documentation says acquiring USDe on external AMMs is permissionless, while direct protocol minting and redemption are limited to approved counterparties that satisfy applicable onboarding requirements. Secondary-market users therefore rely partly on arbitrageurs and market liquidity to transmit the protocol’s backing value into the traded price.
FRAX in 2026: separate the legacy model from frxUSD
Historical FRAX is famous for an evolving algorithmic/collateral model, and FRAX V3 documentation says the protocol targeted a minimum 100% collateralization ratio while using Algorithmic Market Operations (AMOs). AMOs are contracts or controlled mechanisms that can deploy liquidity, lend FRAX, rebalance positions, and conduct other monetary operations under programmed conditions and governance. The legacy architecture is documented in Frax’s FRAX V3 overview and AMO documentation.
For a current security review, however, the relevant dollar product is Frax USD (frxUSD). Current Frax documentation describes frxUSD as fiat-redeemable and fully collateralized, with permitted cash-equivalent reserves such as tokenized U.S. Treasury funds held with regulated custodians. It also states that Frax DAO retains ultimate protocol control while Frax Inc has delegated responsibilities including custodian and reserve management, compliance, attestations, and fiat redemption operations. The official frxUSD documentation is the better starting point for present-day due diligence.
What does this change about decentralization risk?
frxUSD reduces reliance on volatile crypto collateral and perpetual-futures hedging, but it introduces a more institutional reserve chain. A reviewer should examine the legal and operational structure of reserve assets, custodian concentration, minting caps, redemption paths, compliance dependencies, smart contracts, and governance delegation. “Fully collateralized” answers the quantity-of-assets question only if the reserves exist and remain realizable; it does not eliminate custody, legal, liquidity, tokenization, or operational risk.
Frax’s docs also note an important redemption nuance: frxUSD can be redeemable against assets available in its enshrined custodian contracts, but a specific reserve asset is not guaranteed to be available at all times. That is exactly the sort of implementation detail a security review should capture instead of stopping at a headline collateral ratio.
DAI: security through collateral, risk parameters, and liquidation
DAI comes from the system now called the Sky Protocol, formerly MakerDAO. Its classic security model is a multi-collateral debt system: approved assets are locked in Vaults, DAI is generated as debt, and governance sets risk parameters for each collateral type. If a Vault becomes insufficiently collateralized relative to its liquidation threshold, the protocol can liquidate it and sell collateral to cover the obligation.
This architecture makes collateral quality and liquidation performance central. Debt ceilings limit how much DAI can be generated against a collateral type; liquidation ratios determine when positions become vulnerable to liquidation; stability fees influence borrowing economics; and price feeds are needed to value collateral. Sky’s official Multi-Collateral DAI system documentation explains these mechanisms and the Emergency Shutdown design.
DAI’s model should not be simplified to “ETH-backed.” The protocol has long supported multiple governance-approved collateral types, so its risk profile depends on the actual collateral mix and associated structures at the time of review. That can include exposures whose risks extend beyond permissionless crypto. A robust audit therefore evaluates the portfolio rather than relying on DAI’s historical origin story.
DAI and USDS are related but not identical tokens
Sky launched USDS in 2024 alongside a converter between DAI and USDS. Official documentation describes USDS as representing a collateralized balance in the same underlying multi-collateral system, while noting token-level differences. For someone assessing DAI in 2026, Sky’s migration and governance changes are relevant because protocol evolution can alter operational and governance assumptions even when DAI remains in circulation.
Which model is “most decentralized”?
There is no useful one-dimensional answer. Decentralization has several layers: collateral, price discovery, custody, issuance, governance, liquidation, redemption, and operational control. USDe can use crypto-native backing but relies on off-chain hedging infrastructure and centralized derivatives liquidity. Current frxUSD uses institutional reserve assets and custodians while retaining on-chain token and governance components. DAI’s core Vault and liquidation machinery is on-chain, but the security of the whole system still depends on its approved collateral portfolio, governance, oracles and any real-world structures embedded in that portfolio.
A better question is: which failure modes are you willing and able to monitor? A transparent mechanism is not automatically a low-risk mechanism, and decentralization in one layer can coexist with concentrated trust in another.
Practical stablecoin security checklist
Identify the exact token and version. Do not treat legacy FRAX and current frxUSD as the same design, or DAI and USDS as interchangeable at the token layer.
Map assets to liabilities. Ask what economically backs one dollar of supply and whether that backing is overcollateralized, hedged, or held 1:1.
Locate the backing. Separate on-chain contracts from custodians, tokenized funds, exchanges and settlement providers.
Test the redemption path. Determine who can redeem directly, what they receive, whether KYC applies, and what secondary holders depend on during stress.
Inspect liquidity and liquidation assumptions. For DAI, focus on oracle and liquidation performance. For USDe, focus on hedge liquidity, margin and settlement. For frxUSD, focus on reserve liquidity and custodian redemption.
Review concentration. A system can be fully backed yet vulnerable if backing, custody, hedging or governance is concentrated.
Separate yield from principal safety. Staked or savings versions such as sUSDe, sfrxUSD or savings products introduce additional mechanics; do not assume the base stablecoin’s risk profile is identical.
Check governance powers. Document who can change collateral, risk limits, custodians, contracts or emergency settings, and what delays or controls constrain those changes.
Use current primary sources. Stablecoin architectures evolve quickly; verify live documentation, reserve disclosures, governance actions and contract addresses before committing capital.
Bottom line
USDe, frxUSD/FRAX, and DAI illustrate three very different ways to build dollar stability. USDe primarily transforms volatile crypto exposure into a synthetic dollar through offsetting derivatives and operational custody infrastructure. Current frxUSD emphasizes 1:1 cash-equivalent reserve backing and institutional redemption rails, while its FRAX predecessor used a more AMO-centric architecture. DAI relies on a governed portfolio of collateralized debt positions, risk parameters and liquidations.
None of these mechanisms makes a stablecoin risk-free. The useful security comparison is not whether a project calls itself decentralized, but whether its assets, hedges, custodians, liquidations, governance and redemption channels can survive the same stress at the same time. For treasury management or long-term holdings, repeat this review periodically: the system you evaluated six months ago may not have the same collateral composition, governance powers, counterparties or product architecture today.