Home
» News
»
Bitcoin Stock-to-Flow Model: How Accurate Is It in Today’s Market?
Bitcoin Stock-to-Flow Model: How Accurate Is It in Today’s Market?
The Bitcoin Stock-to-Flow model became popular because it offered something investors rarely get from crypto markets: a simple equation tied to a supply schedule that is known years in advance. The idea is intuitive. Bitcoin has a limited stock, new issuance falls every four years or so, and a scarcer asset should, all else equal, command a higher value.
The difficult part is the phrase “all else equal.” In 2026, Bitcoin trades in a market shaped not only by programmed scarcity but also by spot exchange-traded products, interest rates, liquidity, regulation, corporate balance sheets, derivatives, and changing investor demand. That makes Stock-to-Flow useful as a scarcity framework, but much harder to defend as a stand-alone price forecast.
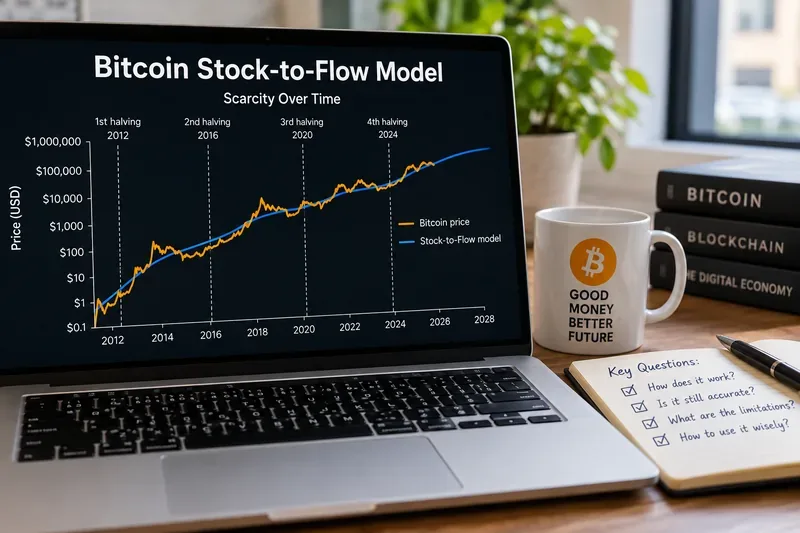
An illustrative Stock-to-Flow chart highlights the model’s core idea: Bitcoin’s issuance falls at halving events, while market prices remain driven by many variables beyond supply scarcity.
What does the Bitcoin Stock-to-Flow model actually measure?
Stock-to-Flow, usually abbreviated S2F, is simply the amount of an asset already in existence divided by the amount newly produced in one year:
Stock-to-Flow = existing stock / annual new supply
A high ratio means annual production is small relative to the existing stock. Gold is often discussed through this lens because new mine production is modest compared with above-ground holdings. Bitcoin makes the concept especially easy to model because issuance is encoded in its protocol rather than determined by mining companies responding to commodity prices.
The original 2019 article by PlanB, “Modeling Bitcoin Value with Scarcity”, fitted a logarithmic relationship between Bitcoin’s market value and its S2F ratio. The paper reported a high historical R-squared and argued that scarcity was a dominant driver of value. It also projected a roughly $55,000 Bitcoin price after the 2020 halving.
That original model should not be confused with PlanB’s later Stock-to-Flow Cross Asset model, or S2FX. S2FX used “phase transitions” and cross-asset comparisons to estimate a much higher roughly $288,000 Bitcoin price for a later market phase. Mixing those two versions makes discussions about whether “S2F worked” unnecessarily confusing.
What changed after the 2024 halving?
Bitcoin’s fourth halving occurred at block 840,000 on April 20, 2024. The block subsidy fell from 6.25 BTC to 3.125 BTC. The official Bitcoin halving reference lists the current 3.125 BTC subsidy and shows that the reward is scheduled to fall again to 1.5625 BTC at the next halving.
If blocks arrive roughly every ten minutes, a 3.125 BTC subsidy implies about 164,250 newly issued BTC per year before accounting for variation in actual block timing. With circulating supply now around 20 million BTC, the rough S2F ratio is therefore around 120. The arithmetic is straightforward: Bitcoin is objectively much scarcer in issuance terms than it was before the 2024 halving.
What does not follow automatically is a specific market price. The halving changes the flow side of the equation. It does not tell us how aggressively institutions will buy, whether leveraged traders will de-risk, how real yields will change, or whether investors will prefer Bitcoin to equities, bonds, gold, or cash.
Has Stock-to-Flow been accurate enough to use for price targets?
The answer depends on what standard you apply.
Question
What the evidence suggests
Does S2F describe Bitcoin scarcity?
Yes. It correctly reflects the declining rate of new issuance created by the halving schedule.
Did the original model capture part of Bitcoin’s long-term rise?
Yes. Its early fit was strong, and the roughly $55,000 post-2020 reference level was eventually exceeded.
Did later S2F-based price projections remain tightly accurate?
No. Later forecasts, especially S2FX’s much higher valuation cluster, were not validated by realized prices.
Can S2F time entries and exits reliably?
Evidence is weak. Academic testing has found important statistical limitations and no clear advantage over simpler approaches.
A useful distinction is between explanatory relevance and forecasting precision. S2F can help explain why Bitcoin’s monetary issuance becomes less inflationary over time. That does not mean the fitted regression can tell an investor where Bitcoin should trade next quarter or even next cycle.
What does academic research say about the model?
The research record is more nuanced than either “S2F was proven” or “S2F is worthless.” A 2022 paper by Thibaut Morillon and Ryan Chacon in Studies in Economics and Finance, “Dissecting the stock to flow model for Bitcoin”, tested the model’s construction and robustness. The authors found that a dynamic version could improve prediction accuracy over time, but they also found that an S2F-based trading strategy was far less profitable than a basic buy-and-hold strategy over their sample.
That matters because Bitcoin’s supply curve and its age both move in one direction. When two trending variables are regressed against each other, a high historical fit can look stronger than the underlying causal relationship really is.
Why is 2026 a harder environment for a supply-only model?
The Bitcoin market has matured. One of the clearest examples is the scale of regulated investment products. In its SEC filing for June 30, 2026, the iShares Bitcoin Trust ETF reported holding 734,261 BTC with a fair value of about $43.4 billion. That single filing illustrates why demand-side variables matter: institutional vehicles can absorb or release large quantities of Bitcoin without any change in the protocol’s issuance rate.
Current market data also shows how far Bitcoin has moved beyond the environment in which the original model was fitted. Coinbase’s Bitcoin market page showed roughly 20 million BTC in circulating supply and a market capitalization around $1.5 trillion in mid-September 2026. The supply curve remains predictable; the valuation placed on that supply changes continuously.
For an investor, that means a better question is not “What price does S2F predict?” but “How much explanatory weight should scarcity receive relative to demand, liquidity, and macro conditions?”
Should you still use Stock-to-Flow in 2026?
Yes, if you use it for the right job.
Use S2F if your question is about structural scarcity
S2F is useful for comparing how Bitcoin’s new issuance changes across halving eras. It helps answer questions such as: How quickly is supply expanding? How much new Bitcoin reaches the market relative to the stock already outstanding? How dramatically did the 2024 halving reduce new supply?
Do not use S2F alone for a precise price target
A model with no demand variable cannot explain why two periods with nearly identical issuance conditions can produce very different prices. For price decisions, investors should also examine spot demand, ETF creation and redemption activity, liquidity conditions, leverage, realized volatility, monetary policy, and valuation measures derived from on-chain or market data.
Do not treat the model line as a trading signal
Being “below the model” does not prove Bitcoin is undervalued, and being “above the model” does not prove it is overvalued. A regression line fitted to past data is not a guaranteed equilibrium price.
What should you compare with S2F before making a decision?
A practical framework is to separate the investment case into four layers:
Supply: halving schedule, current block subsidy, circulating supply, and long-term issuance.
Demand: ETF holdings and flows, corporate treasury demand, exchange activity, and broad investor participation.
Market structure: liquidity, derivatives positioning, leverage, volatility, and concentration of holdings.
Macro and policy: interest rates, real yields, dollar conditions, regulation, and risk appetite.
S2F covers mainly the first layer. That is not a flaw if it is treated as a specialized tool. It becomes a problem only when one supply metric is promoted into a complete valuation model.
So, is the Bitcoin Stock-to-Flow model still relevant?
It is relevant as a description of Bitcoin’s engineered scarcity and as a historical model that helped popularize the economic significance of halvings. It is much less convincing as a stand-alone forecasting engine for today’s market.
The strongest reason to keep S2F in an analytical toolkit is not that it can produce a precise future price. It is that Bitcoin’s issuance schedule is unusually transparent, and S2F summarizes that feature in one number. The strongest reason not to rely on it alone is equally simple: price is set where supply meets demand, and S2F models only one side of that equation.
For current market decisions, treat Stock-to-Flow as a scarcity indicator, not a destination price. If an investment thesis still looks attractive after adding demand, liquidity, macro conditions, valuation, and risk management, then S2F can provide useful context. If the thesis works only because a model curve says price “should” be higher, the analysis is too fragile.
This article is for educational purposes and does not constitute investment advice. Cryptocurrency prices are volatile, and historical model fit does not guarantee future performance.