Home
» News
»
Flash Loans in DeFi: How Traders Use Uncollateralized Loans for Arbitrage
Flash Loans in DeFi: How Traders Use Uncollateralized Loans for Arbitrage
Flash loans are one of DeFi’s most unusual building blocks: a trader can borrow a large amount of on-chain liquidity without posting collateral first, use that liquidity inside a transaction, and repay the loan before the transaction finishes. If repayment cannot be completed, the entire transaction reverts. That atomic design is what makes an uncollateralized loan possible without giving the borrower time to simply disappear with the funds.
For arbitrage traders, the practical goal is not “borrow as much as possible.” The goal is to identify a price difference large enough to survive every cost and execution risk in the same atomic transaction. A flash-loan trade is only high quality when the final on-chain outcome repays principal and required premium, covers swap fees and gas, tolerates expected slippage, and still leaves a positive net return. If those conditions are not present, using more borrowed capital usually magnifies execution problems rather than creating an edge.
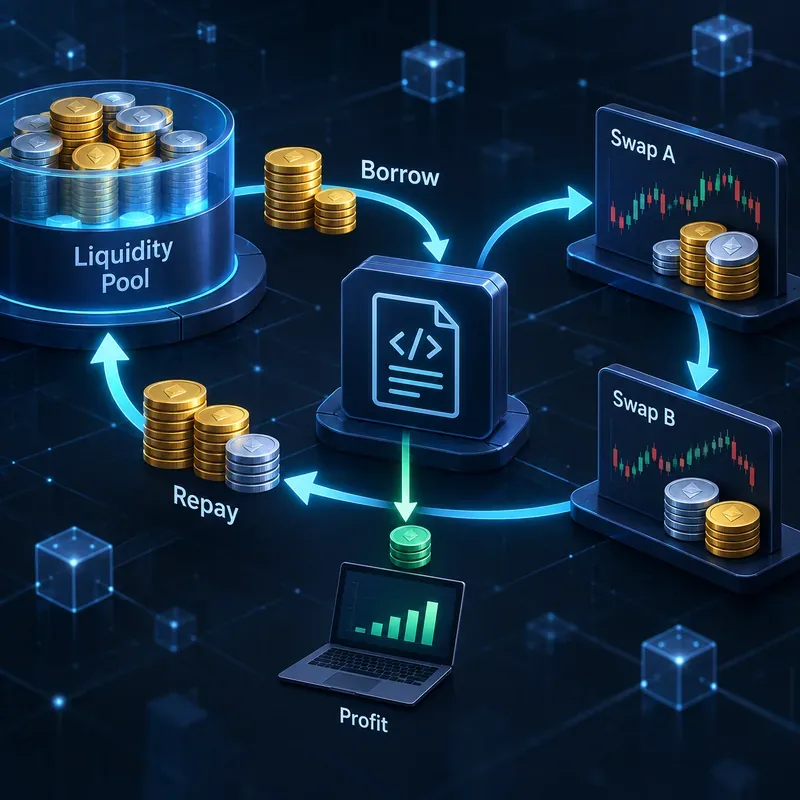
A flash-loan arbitrage transaction succeeds only if the borrow, swaps, repayment, and any remaining profit can all be completed atomically.
What a flash loan actually does
Traditional lending usually relies on collateral, credit checks, or legal enforcement because repayment happens later. A flash loan changes the timing. The smart contract lends assets and requires the debt to be settled before the transaction ends. If the required balance is not returned, the blockchain rolls the whole transaction back.
That same-transaction property is closely related to the “flash swaps” described in the Uniswap V2 whitepaper, where a user can receive an asset, use it elsewhere, and then pay for or return it before the transaction completes. Aave also exposes dedicated flash-loan functionality through its protocol contracts. The exact fee and available assets depend on deployment and governance configuration, so traders should verify the live market rather than hard-coding assumptions.
As a current reference point, Aave’s 2026 Ethereum V4 activation proposal states that the intended flash-loan configuration matches the then-current V3 Ethereum setup with a total premium of 5 basis points, or 0.05%. It also describes fee waivers for approved flash borrowers. Because governance can change parameters and deployments differ, this figure is best treated as a dated configuration reference rather than a universal DeFi fee. See the Aave V4 Ethereum activation proposal for the stated parameters.
How flash-loan arbitrage works
The simplest pattern is cross-market arbitrage. Suppose Token X can be bought for less on one decentralized exchange than it can be sold for on another. A trader’s contract can borrow a stablecoin, buy Token X on the cheaper venue, sell Token X on the more expensive venue, repay the flash loan plus any premium, and keep the remainder.
A simplified transaction might look like this:
Borrow 1,000,000 units of a stablecoin through a flash-loan provider.
Use the borrowed stablecoin to buy Token X on DEX A.
Immediately sell Token X on DEX B where the executable price is higher.
Repay the 1,000,000 principal plus the provider’s required premium.
Keep the residual amount only if the transaction remains profitable after all costs.
The important word is executable. A quoted price difference is not the same thing as realizable profit. Automated market maker prices move as the trade consumes liquidity. A route that looks attractive for $10,000 may become unprofitable at $1 million because price impact expands faster than the nominal spread.
What a profitable result should look like
A good flash-loan arbitrage system should evaluate net outcome, not gross spread. The minimum useful calculation is:
Net profit = arbitrage proceeds − borrowed principal − flash-loan premium − DEX fees − gas − other execution costs.
In practice, a trader should also include a safety margin for price movement between simulation and inclusion. If a route is profitable only under the exact quote observed a moment earlier, the strategy is fragile.
Check
Healthy sign
Warning sign
Net profit
Positive after all modeled fees and gas
Profit exists only before transaction costs
Price impact
Trade size stays within a tested liquidity range
Borrow size causes the spread to collapse
Simulation
Full atomic route succeeds against recent chain state
Only individual swaps were tested
Slippage tolerance
Limits protect the trade from materially worse fills
Unlimited or overly loose minimum-output settings
Competition
Profit remains after realistic inclusion assumptions
Edge disappears if another searcher acts first
Example: why the headline spread can be misleading
Assume a trader sees what appears to be a 0.30% price gap and considers a $1,000,000 flash loan. The gross theoretical spread is $3,000. That sounds attractive until costs are added. If the flash-loan premium were 0.05%, that alone would be $500. Two swaps may each charge trading fees. The first trade can push the buy price upward, while the second can push the sell price downward. Gas and any builder or inclusion payments add more cost.
If price impact and swap fees consume $2,200 and gas plus other execution costs consume another $400, the apparent $3,000 opportunity becomes a $100 loss after the $500 flash-loan premium. The exact numbers vary by chain, pool, fee tier, route, and transaction path, but the lesson is durable: gross spread is only a screening signal.
Why traders use flash loans instead of their own capital
Flash loans can make capital-intensive arbitrage accessible to a smart contract that does not hold the full notional amount beforehand. That can improve capital efficiency for strategies that need temporary liquidity only for the duration of a transaction.
They can also be useful beyond two-venue arbitrage. Developers may use atomic liquidity for collateral swaps, debt refinancing, liquidations, or multi-step position management. Aave’s own materials describe flash-liquidity use in position-management flows, including whitelisted integrations where fees can be reduced or waived. A May 2026 Aave Labs development update notes that CoW adapters were whitelisted as flash borrowers across Aave V3 markets, allowing those adapter routes to use zero-fee flash liquidity for certain Aave swaps. See the Aave Labs May 2026 development update.
That does not mean flash loans automatically make a strategy profitable. They remove the need to pre-fund the borrowed principal; they do not remove trading fees, gas, competition, smart-contract bugs, or adverse price movement.
The four constraints that most often decide whether arbitrage works
1. Liquidity depth
The displayed price can be attractive while the available depth is too small. Before sizing a flash loan, the route needs to be simulated at the intended notional amount. A profitable $50,000 trade cannot be assumed to scale linearly to $5 million.
2. Slippage and pool fees
Every swap changes pool reserves and may pay a liquidity-provider fee. The route should use minimum-output or equivalent protections so that a worse-than-expected fill causes a revert rather than silently converting a winning trade into a losing one.
3. Gas and transaction inclusion
Atomic execution does not guarantee favorable ordering. Other searchers may observe the same opportunity, submit competing transactions, or alter the state before the trade lands. A route should be evaluated under realistic gas and inclusion assumptions, not just under an ideal local simulation.
4. Contract correctness
The transaction is only as safe as the code that orchestrates borrowing, swaps, approvals, callbacks, and repayment. Errors in token approvals, decimal handling, callback validation, or routing logic can cause reverts or expose funds held by the contract. Mature implementations generally rely on extensive testing, transaction simulation, and narrowly scoped permissions.
Flash loans are not the same thing as flash-loan attacks
The term “flash-loan attack” can be misleading. A flash loan is a liquidity primitive. It may provide large temporary capital that makes an exploit economically feasible, but the underlying vulnerability is usually elsewhere: for example, insecure oracle design, flawed accounting, manipulable pricing logic, or a smart-contract bug.
This distinction matters when judging protocol risk. Disabling flash loans does not automatically fix a protocol that trusts a manipulable spot price. Conversely, a well-designed protocol can safely coexist with flash liquidity if its invariants, oracle model, and accounting remain secure under adversarial transaction sequences.
When to change the approach
A disciplined trader should abandon or redesign a route when the economics depend on unrealistic assumptions. Common reasons include persistent negative profit after simulation, excessive sensitivity to small price moves, inadequate liquidity at the desired trade size, or execution that regularly loses to faster searchers.
There are several alternatives. The trader can reduce notional size to lower price impact, route through deeper pools, use a different chain with lower execution costs, or wait for a wider spread. Sometimes the correct decision is simply not to trade. A flash loan is most useful when it solves a temporary capital constraint; it is not a substitute for an actual pricing edge.
Practical quality checklist before deploying capital
Verify the flash-loan provider, available asset, maximum usable liquidity, and current premium on the target deployment.
Simulate the complete transaction against recent chain state, including the borrow, every swap, repayment, and profit transfer.
Measure price impact at the intended notional amount rather than relying on top-of-pool quotes.
Include flash-loan fees, pool fees, gas, and realistic transaction-inclusion costs in the profitability threshold.
Set explicit minimum outputs or other bounds so adverse execution reverts safely.
Test failure paths, token decimal handling, approvals, callbacks, and repayment logic.
Use a required profit buffer instead of accepting trades that are only marginally positive in simulation.
Re-check assumptions whenever protocol fees, pool liquidity, routing, or market competition changes.
Bottom line
Flash loans make it possible to borrow substantial DeFi liquidity without upfront collateral because repayment is enforced inside one atomic transaction. For arbitrage, that can remove a major capital constraint, but it does not create profit by itself. The real edge comes from an executable price discrepancy that remains positive after flash-loan premiums, exchange fees, slippage, gas, and competition.
The most useful way to judge a flash-loan strategy is therefore by its final transaction outcome: does the complete route repay everything it owes, stay within defined execution limits, and leave a meaningful net profit under realistic conditions? If not, the right response is to resize, reroute, or skip the trade rather than assume that more borrowed liquidity will improve the result.