Home
» News
»
Global Liquidity Index (M2): Is It Really the Strongest Macro Indicator for Crypto Rallies?
Global Liquidity Index (M2): Is It Really the Strongest Macro Indicator for Crypto Rallies?
Bottom line: global M2 is a useful macro backdrop for crypto, but calling it “the strongest” macro indicator overstates what the evidence can support. A rising broad-money trend can coincide with easier financial conditions and greater appetite for risk assets, yet there is no single official “Global Liquidity Index (M2),” no fixed lead time between liquidity and Bitcoin, and no guarantee that more money supply will produce a crypto rally. The best use of global M2 is as one layer in a broader regime framework, not as a standalone buy signal.
This distinction matters because many viral charts make the relationship look cleaner than it is. They often aggregate national money-supply series, convert them into U.S. dollars, shift one line forward by a chosen number of weeks, and then compare the result with Bitcoin. That can be informative, but it can also introduce exchange-rate effects, inconsistent definitions, publication lags, and hindsight bias.
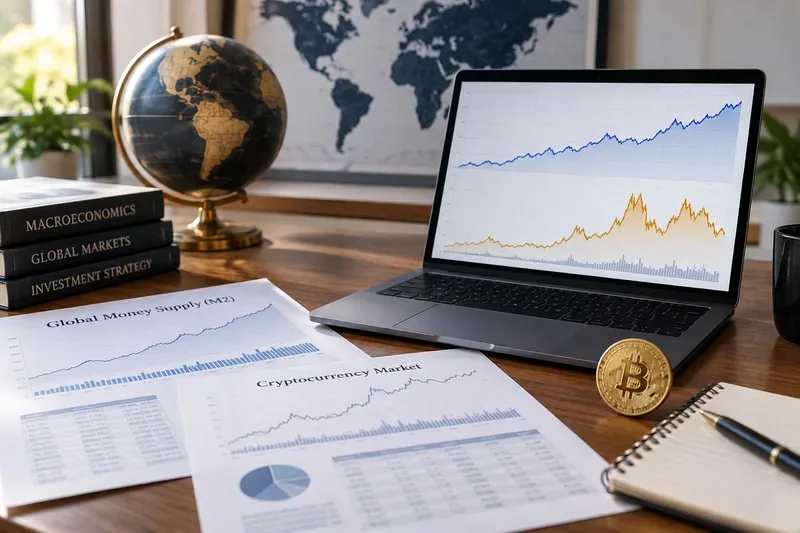
A macro research desk with global money-supply reports and crypto market charts, illustrating why liquidity data should be compared with market prices rather than treated as a standalone signal.
First misconception: “Global M2” is an official worldwide index
Verified: national and regional authorities publish monetary aggregates, but there is no single globally standardized official M2 index used by all major central banks. In the United States, the Federal Reserve publishes M2 in its H.6 release. The euro area publishes several aggregates through the European Central Bank, with M3 used as the broadest headline measure. Japan publishes money-stock statistics through the Bank of Japan. China publishes broad money M2 through the People’s Bank of China. Definitions, sector coverage, seasonal adjustment, and instrument treatment differ across jurisdictions.
The Federal Reserve’s current H.6 release, dated August 25, 2026, shows seasonally adjusted U.S. M2 at $23.218 trillion for July 2026, versus $22.026 trillion in July 2025. The Fed defines M2 as M1 plus small-denomination time deposits and retail money-market fund balances, less specified IRA and Keogh balances. The Fed also changed the netting methodology for those retirement-account balances in July 2026, applying the methodology back through the historical series. That is a reminder that even mature monetary datasets can be revised or redefined. See the Federal Reserve H.6 Money Stock Measures.
Action: whenever you see a “global M2” chart, check its construction notes. Identify which economies are included, which broad-money series were used, whether the data are seasonally adjusted, and how the author handles revisions.
Second misconception: BIS global liquidity is the same thing as global M2
Verified: the Bank for International Settlements uses “global liquidity” in a different and broader sense. The BIS defines global liquidity as the ease of financing in global financial markets. Its official Global Liquidity Indicators track credit to non-bank borrowers, especially foreign-currency credit in U.S. dollars, euros, and Japanese yen. That includes bank lending and international debt securities rather than simply summing national M2 balances.
The BIS has repeatedly cautioned that global liquidity is not directly observable and cannot be summarized completely by one indicator. Its research emphasizes multiple dimensions: funding conditions, credit supply, credit demand, and market liquidity. The BIS overview is available at BIS Global Liquidity Indicators, while its background note explains why no single metric captures the full concept.
As of the BIS statistical release published September 14, 2026, the latest GLI reference period was end-March 2026. The BIS reported that U.S. dollar-denominated foreign-currency credit grew 7.3% year over year in Q1 2026 to $14.7 trillion, while euro-denominated foreign-currency credit grew 12% to €5.1 trillion. Those figures measure cross-border financing conditions, not “global M2.” See the BIS release on international banking statistics and global liquidity.
Action: use different labels for different concepts. If you are tracking summed broad money, call it “global broad money” or “global M2 composite.” If you are tracking cross-border foreign-currency credit, call it a BIS global-liquidity measure.
Why M2 can matter for crypto
Verified in principle: monetary aggregates can reflect changes in deposit creation, financial intermediation, credit conditions, and the amount of liquid purchasing power held by households and firms. Research from the IMF has examined global liquidity through monetary aggregates and found that broad-money measures contain information about cross-border financial conditions and non-core bank funding. See the IMF working paper Global Liquidity through the Lens of Monetary Aggregates.
Conditional: crypto tends to behave like a high-beta risk asset during many macro regimes. When liquidity is improving, real yields are falling, the dollar is weakening, credit stress is contained, and investors are willing to take duration and volatility risk, Bitcoin and other crypto assets may benefit. But the transmission mechanism is indirect. M2 does not flow automatically into Bitcoin. It first interacts with banking behavior, portfolio allocation, interest rates, leverage, exchange rates, and investor expectations.
Action: treat rising global M2 as evidence that the macro environment may be becoming more supportive, then confirm that signal with market-based indicators such as real yields, the U.S. dollar, credit spreads, equity breadth, and crypto-specific flows.
Why a U.S.-dollar global M2 chart can be misleading
A common construction method converts each country’s broad-money stock into U.S. dollars and adds the results. That creates a useful common unit, but it also makes the index sensitive to foreign-exchange moves. If the dollar weakens, the U.S.-dollar value of euro-, yen-, or yuan-denominated money stocks can rise even when local-currency money growth has barely changed. A stronger dollar can do the reverse.
This is especially important in crypto because Bitcoin itself is usually quoted in dollars. A falling dollar can simultaneously lift the dollar value of foreign M2 and support dollar-denominated risk assets. The apparent relationship may therefore partly reflect a shared currency factor rather than a direct causal link from broad money to Bitcoin.
Action: compare at least two versions of the signal: a USD-converted global broad-money series and a local-currency growth composite. If both are accelerating, the liquidity message is stronger than when only the FX-converted series is rising.
Why the popular 8-to-12-week “lead” should not be treated as a law
Not established: there is no official or universally validated rule that global M2 leads Bitcoin by a fixed number of days or weeks. The best-fitting lag can change across cycles, especially when researchers choose the lag after seeing the price outcome. Shifting one series until two peaks line up may produce an attractive chart without establishing predictive power.
Lead-lag relationships can also break when crypto-specific events dominate. Exchange failures, regulatory changes, stablecoin stress, ETF flows, leverage liquidations, protocol failures, hacks, or a sudden risk-off shock can overwhelm a supportive macro liquidity trend. Conversely, crypto can rally during a mediocre money-supply backdrop if a powerful asset-specific catalyst appears.
Action: if you test a lead, define it before the next observation. For example, track the same 8-week or 12-week lag for a full out-of-sample period rather than changing the lag whenever the chart stops fitting.
Is global M2 really the strongest macro indicator for crypto rallies?
What can be said: global broad-money growth deserves a place near the top of a crypto macro dashboard because crypto is highly sensitive to liquidity and risk appetite. But “strongest” is not a verified universal ranking. The answer depends on the period, the asset, the sampling frequency, the exact construction of the M2 composite, and the competing indicators used in the test.
Earlier IMF research on asset prices found that global liquidity could have meaningful effects in some markets but not uniformly across all asset classes. The paper Can Global Liquidity Forecast Asset Prices? found stronger evidence for housing than equities in its historical sample. That study predates modern crypto markets, so it cannot prove or disprove a Bitcoin-specific claim. It does, however, reinforce the broader lesson that liquidity relationships are asset- and regime-dependent.
Action: rank indicators by the question you are asking. Use M2 for medium-term liquidity regime analysis, market prices for real-time confirmation, and crypto-native data for asset-specific positioning.
A practical crypto liquidity dashboard
Indicator
What it helps answer
Main limitation
Global broad-money growth
Is liquid money growth accelerating across major economies?
No standardized global M2 definition; revisions and FX conversion matter.
BIS global liquidity
Is cross-border foreign-currency credit expanding or contracting?
Quarterly and slower-moving; concept differs from M2.
Real interest rates
Is the opportunity cost of holding non-yielding or long-duration assets rising?
Can be overridden by growth or crisis expectations.
U.S. dollar trend
Are global financial conditions tightening through dollar strength?
Relationship with crypto can change temporarily.
Credit spreads
Is risk appetite healthy or deteriorating?
Traditional credit markets may react differently from crypto.
Stablecoin supply and exchange flows
Is crypto-native liquidity expanding inside the ecosystem?
Supply growth does not equal immediate buying demand.
ETF and fund flows
Is institutional demand entering or leaving?
Can be noisy and concentrated in a few products.
Action: avoid making a directional trade from one green light. A stronger setup is when global broad money is accelerating, real yields are stable or falling, the dollar is not surging, credit spreads are calm, and crypto-native flows confirm demand.
How to build a cleaner global M2 composite
1. Start with official national sources
Use the central-bank or statistical-agency series directly. For the United States, use the Fed H.6 data. For the euro area, the ECB publishes monetary aggregates; its July 2026 monetary-development release reported M3 growth of 3.4% year over year and showed short-term deposits outside M1 as part of the M2 structure. See the ECB monetary developments release for July 2026. Japan’s latest money-stock releases are listed on the Bank of Japan Money Stock page.
Action: document the exact series code and definition for each economy so your historical updates remain consistent.
2. Decide whether you want levels or growth rates
A level series answers “how much broad money exists?” A growth-rate series answers “is liquidity expanding faster or slower?” For market analysis, the change in the growth rate can sometimes be more informative than the absolute level because asset prices react to changes in the expected liquidity impulse.
Action: track year-over-year growth and a shorter momentum measure, such as three-month annualized growth, alongside the total level.
3. Separate the FX effect from the local money effect
If you convert everything to dollars, also calculate the composite using indexed local-currency growth. That lets you see whether the signal comes from actual money growth or from currency translation.
Action: when the two versions diverge, flag the signal as FX-sensitive rather than interpreting it as a clean monetary impulse.
4. Use publication dates, not only observation dates
Money data are released with lags and can be revised. A backtest that assumes you knew July M2 on July 31 can accidentally use future information if the release was published weeks later.
Action: maintain a “data available as of” date in every historical test. This is essential if you want to know whether the indicator actually had forecasting value in real time.
What is verified, what is conditional, and what remains unknown?
Verified: major monetary authorities publish broad-money aggregates, and money/credit conditions are meaningful components of global financial liquidity.
Verified: the BIS explicitly says global liquidity is multidimensional and cannot be captured fully by one indicator.
Conditional: expanding global broad money can support crypto when it coincides with easier financial conditions and improving risk appetite.
Conditional: a USD-converted global M2 composite can correlate with Bitcoin partly because both react to the dollar and global risk conditions.
Not established: a fixed global-M2 lead of a specific number of weeks predicts Bitcoin reliably across all cycles.
Not established: global M2 is universally the single “strongest” macro indicator for every crypto rally.
Action: use this classification whenever you encounter a confident social-media claim. Ask whether it is a measurement fact, a regime-dependent relationship, or an untested forecasting assertion.
Final takeaway
Global M2 is valuable because it forces crypto investors to look beyond token narratives and ask a broader question: is the world’s financial system becoming more or less liquid? That is a productive question. The mistake is turning a useful macro lens into a deterministic price formula.
The most robust approach is to use a global broad-money composite as a medium-term regime indicator, keep BIS credit measures separate, control for foreign-exchange effects, respect publication lags, and confirm the macro message with market prices and crypto-native flows. When those signals align, the case for a liquidity-supported rally becomes stronger. When they conflict, the conflict itself is information—and a reason to reduce confidence rather than force the chart to fit.
Data and source check: September 15, 2026. Monetary and liquidity series are subject to subsequent revisions. This article is educational and does not provide investment advice.