Home
» News
»
How RWA Protocols Generate Real-World Yield Across Bear and Bull Markets
How RWA Protocols Generate Real-World Yield Across Bear and Bull Markets
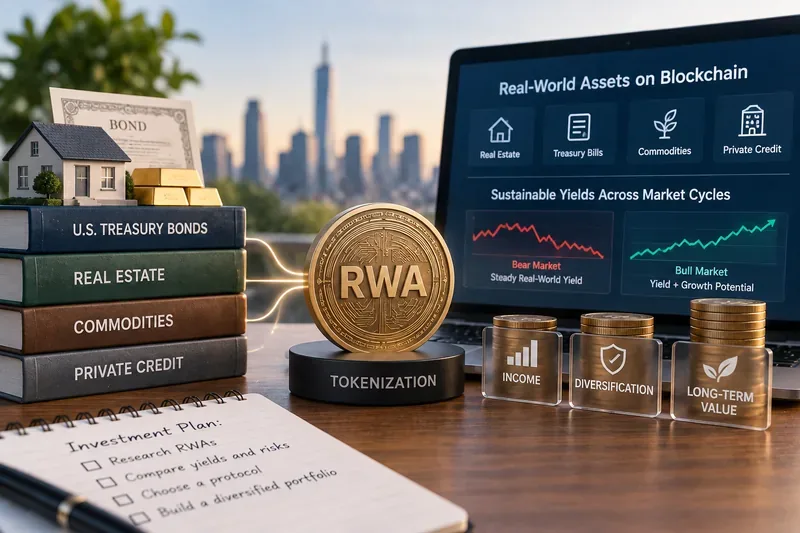
Real-world asset (RWA) protocols can produce yield in both crypto bear and bull markets because the cash flow often comes from offchain assets rather than token emissions. But “real-world yield” is not one thing. A token backed by short-term U.S. Treasuries behaves very differently from a private-credit pool, and both differ from a structured pool of loans, receivables, or other tokenized assets.
That distinction is especially relevant in 2026. The U.S. Securities and Exchange Commission clarified in January 2026 that a tokenized security remains a security; putting an asset on a blockchain does not change its legal substance or the rights attached to it. At the same time, tokenized Treasury and credit products have continued to expand, giving onchain investors more ways to earn income that is not directly dependent on rising crypto prices. See the SEC's January 2026 statement on tokenized securities.
RWA yield can come from Treasury interest, credit coupons, rent, receivables or other offchain cash flows. The blockchain changes distribution and settlement, not the underlying economic source of return.
What makes an RWA yield “real”?
A useful definition is simple: the yield should be traceable to an identifiable economic activity or asset outside the protocol's own token incentives. Examples include interest paid by the U.S. government on Treasury bills, interest paid by a borrower on a secured loan, rental income, invoice payments, or cash flows from a securitized portfolio.
This is different from a strategy whose headline APY is mostly funded by newly issued governance tokens. Token incentives can be useful for bootstrapping liquidity, but they depend on continued demand for the token and can shrink quickly when market sentiment changes. RWA cash flows can also fall, default, or become illiquid, but their source is easier to identify and analyze.
“Sustainable” therefore should not mean “guaranteed.” It means the return has an external economic source that can continue even if crypto prices stop rising.
The three main RWA yield models
Model
Primary source of yield
Main advantage
Main trade-off
Tokenized Treasuries / cash equivalents
Government bills, money-market funds, bank deposits
High-quality collateral and relatively predictable income
Yield falls when short-term interest rates fall; eligibility restrictions may apply
Private or institutional credit
Interest paid by borrowers
Potentially higher income than government bills
Credit, collateral, counterparty and liquidity risk
Structured asset pools
Loans, receivables, securitized assets, fund cash flows
Can diversify beyond one borrower or one asset type
More complex underwriting, valuation and redemption mechanics
Choice 1: Tokenized Treasuries for liquidity and lower credit risk
Tokenized Treasury products are the most direct example of RWA yield that is largely independent of crypto market direction. The underlying return comes from U.S. government securities or funds holding them.
Ondo's OUSG, for example, provides exposure primarily to short-term U.S. Treasuries and money-market funds. Ondo's current documentation says the portfolio can include funds from BlackRock, Franklin Templeton, WisdomTree, Fidelity and others, along with bank deposits and USDC for liquidity. As of September 10, 2026, Ondo displayed a 30-day yield of about 3.46% for OUSG. The product page is available at Ondo OUSG.
That yield is understandable because it is anchored to short-term interest rates. The Federal Reserve's H.15 release for September 11, 2026 showed a 3-month Treasury bill secondary-market rate of about 3.92%. The exact yield received by a token holder can differ because of fund expenses, cash balances, portfolio composition, timing and other costs. The official reference is the Federal Reserve H.15 Selected Interest Rates.
When this model fits
You prioritize capital preservation over maximum yield.
You want an onchain cash-management asset rather than directional crypto exposure.
You value shorter duration and relatively transparent underlying assets.
You expect to need liquidity more often than a private-credit investor would.
What you give up
The most obvious trade-off is return. Treasury-backed products should not be expected to consistently pay as much as riskier credit. Their yield also changes with monetary policy. If the Federal Reserve cuts rates substantially, short-term Treasury income usually falls too.
Access can be another limitation. OUSG is a qualified-access product; Ondo states that investors must meet eligibility standards such as accredited-investor and qualified-purchaser requirements. Its eligibility documentation explains those restrictions.
For non-U.S. investors, Ondo's USDY illustrates a somewhat different structure. As of September 2026, Ondo described USDY as a freely transferable yield-bearing token secured by U.S. Treasuries and bank deposits and showed a 3.60% APY. However, USDY has jurisdictional eligibility restrictions and is not available to U.S. persons. See Ondo USDY.
Choice 2: Private credit for higher income with more underwriting risk
Private-credit RWA products earn yield from borrowers rather than from the government. That usually creates room for higher rates, but the investor is being paid to accept additional risks.
Maple's secured-lending products are a current example. Maple says its institutional lending pools extend overcollateralized loans to institutional borrowers, with interest rates determined through underwriting and loan terms. As of mid-September 2026, its institutional secured-lending page showed about 5.3% net APY, roughly 148% collateral coverage and a stated maximum time to liquidity of 30 days. Current figures can change and should be checked on the Maple Institutional secured-lending page.
The extra yield relative to short-term government bills has an economic explanation: lenders are accepting borrower default risk, collateral-value risk, legal-enforcement risk and potentially slower withdrawals.
When this model fits
You want more income than a Treasury strategy may provide.
You are comfortable reviewing borrower quality, collateral and loan-to-value ratios.
You can tolerate slower liquidity.
You understand that “overcollateralized” does not mean “risk-free.”
What to monitor
For credit products, headline APY is less important than how the lender is protected. Look at collateral quality, loan-to-value ratio, custody, margin-call processes, borrower concentration, legal recourse, historical defaults and withdrawal terms.
Maple's own underwriting documentation says its yield is generated through secured institutional lending and that borrowers undergo KYC/AML checks, financial analysis and collateral review. That is the real reason the yield can persist across different crypto price regimes: borrowers pay for access to capital. But if collateral falls rapidly or borrowers become stressed, the lender can still suffer losses. See Maple's yield generation and risk-management explanation.
Choice 3: Structured pools for diversification and customized risk
Centrifuge represents another model: tokenize and pool financial assets, then let investors buy exposure to a share class. The assets can include loans, invoices or other financial claims, and pools can use senior and junior tranches to divide risk.
In a traditional securitization structure, a junior tranche absorbs losses first and can receive higher returns, while a senior tranche receives lower returns but has more protection. Centrifuge's documentation describes this same basic architecture and also supports onchain net asset value calculations and write-downs for impaired assets. See the official Centrifuge securitization documentation.
When this model fits
You want exposure to a diversified portfolio rather than one borrower.
You are willing to analyze pool composition and waterfall rules.
You want to choose between senior and junior risk profiles.
You can accept less immediate liquidity in exchange for access to longer-duration assets.
The key trade-off
Structured pools can reduce single-borrower concentration, but they introduce complexity. Investors must understand who originates the assets, how they are valued, who services them, how defaults are handled, when redemptions are processed and which tranche takes losses first.
Tokenization can make reporting and settlement more transparent, but it does not eliminate the underlying credit work.
Why RWA yield can survive a crypto bear market
In a bear market, token prices can fall sharply while a Treasury bill continues accruing interest or a borrower continues making contractual loan payments. This weak correlation between the yield source and crypto price is the central appeal of RWA strategies.
For Treasury-backed assets, the main driver is interest-rate policy, not Bitcoin's price. For private credit, the main drivers are loan demand, borrower solvency, collateral coverage and credit spreads. For structured pools, performance depends on the cash flows and defaults of the underlying assets.
That does not mean a crypto bear market is irrelevant. It can reduce the value of crypto collateral, increase borrower stress, create stablecoin liquidity pressure and make secondary-market exits harder. A real-world yield source can be independent of crypto prices while the wrapper around it remains exposed to blockchain and market risks.
Why bull markets create a different trade-off
In a strong bull market, RWA yields may look less attractive compared with rapidly appreciating crypto assets. A 3%–6% annual yield can feel modest when speculative tokens are moving double digits in a week.
But that comparison mixes income and capital gains. Treasury or credit yield can serve a different portfolio role: preserving dry powder, earning on stable-value reserves or reducing total volatility. The investor gives up some upside in exchange for more predictable cash flow.
Private-credit demand can also increase during bull markets as trading firms, market makers, miners and other institutions borrow more. That can support higher credit spreads, but a hot market can also encourage weaker underwriting. Higher loan demand is only beneficial if credit standards remain disciplined.
How to compare RWA protocols in practice
Question
Why it matters
What exactly generates the yield?
Separates external cash flow from token incentives.
Who legally owns the underlying asset?
Determines your actual claim if something fails.
Who holds custody?
Reveals counterparty and bankruptcy exposure.
How frequently is NAV or collateral updated?
Shows how quickly deterioration may become visible.
What is the redemption window?
Affects whether the asset behaves like cash or like private credit.
Is access permissioned?
Some products require KYC, jurisdictional eligibility or minimum investment sizes.
Does APY include incentives?
Distinguishes economic yield from temporary subsidies.
What happens in default?
Tests whether legal and liquidation protections are real.
Which model is best for different needs?
For onchain cash management
Short-duration Treasury-backed products are usually the clearest fit. Their return is easier to benchmark against government rates, and their assets are generally more liquid than private loans. The cost is lower potential yield and often stricter access rules.
For higher income
Secured private credit may be more appropriate if you can tolerate borrower and collateral risk. Focus on underwriting quality and withdrawal terms rather than simply choosing the highest APY.
For diversified credit exposure
Structured pools can make sense when you want a portfolio of real-world loans or receivables and are comfortable analyzing tranches, servicing and NAV methodology.
For maximum DeFi composability
Freely transferable yield-bearing tokens can be attractive because they can sometimes be used as collateral or integrated into other protocols. That creates additional utility, but each extra protocol layer also adds smart-contract, oracle, liquidity and liquidation risk.
The limits of “sustainable yield”
No RWA protocol escapes economic cycles. Treasury yields fall when policy rates fall. Credit losses rise when borrowers weaken. Real-estate income can decline. Redemptions can slow when assets are illiquid. Stablecoins used for settlement can introduce another layer of issuer risk.
There is also a legal distinction between owning a token and owning the underlying asset directly. The SEC emphasized in 2026 that tokenized securities can be structured in different ways and can provide different rights to holders. Investors need to understand whether the token is issuer-sponsored, a fund share, a note, a third-party entitlement or another legal claim.
Finally, onchain transparency has boundaries. You may be able to see token balances and transfers in real time while still depending on an administrator, custodian, auditor or asset servicer for the offchain facts.
Bottom line
RWA protocols can make yield less dependent on whether crypto is in a bear or bull market by connecting onchain capital to offchain cash flows. Treasury-backed products generally offer the cleanest link to low-risk rates. Private credit can offer higher income in exchange for underwriting and liquidity risk. Structured pools can diversify exposures but require more analysis.
The best choice depends on the job you want the asset to do. If the goal is cash management, prioritize liquidity and asset quality. If the goal is higher income, accept that credit risk is the source of the spread. If the goal is diversification, examine pool construction and loss waterfalls. In every case, prefer yield you can trace to a real economic source, understand who controls the underlying assets, and treat any advertised APY as a current snapshot rather than a promise.