Home
» News
»
Long-Term Holder vs. Short-Term Holder Behavior: BTC On-Chain Metrics Explained
Long-Term Holder vs. Short-Term Holder Behavior: BTC On-Chain Metrics Explained
The most important point: Bitcoin’s long-term holder (LTH) and short-term holder (STH) metrics are best used as behavioral context, not as automatic buy or sell signals. They help answer three practical questions: which coins are becoming dormant, which coins are being spent, and whether the coins moving are doing so above or below their on-chain cost basis. If you separate those three ideas—supply, spending, and profitability—the data becomes much easier to read.
There is also a critical limitation to understand before using any chart: an LTH or STH label is not a verified identity. On-chain analytics classify coins or estimated entities using observed blockchain behavior. They cannot directly know whether a transfer was a sale, a self-transfer, a custodian reshuffle, or an investor changing wallets. That distinction should shape every interpretation that follows.
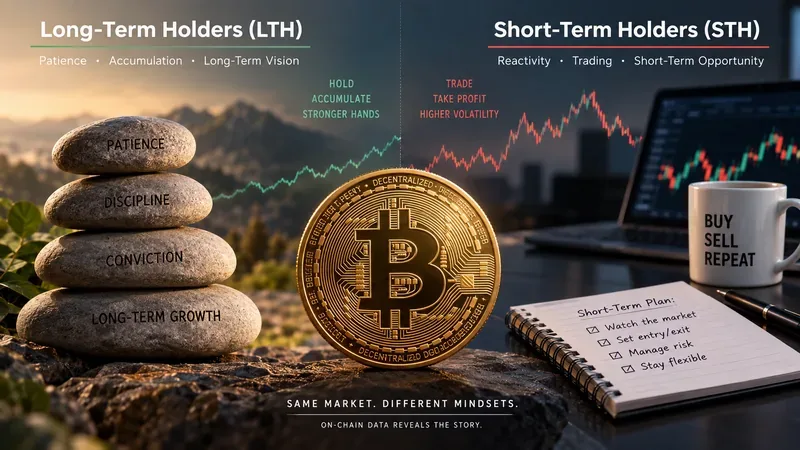
A conceptual contrast between longer-duration and shorter-duration Bitcoin behavior. In on-chain analytics, LTH and STH are statistical cohorts based on coin or entity age—not verified descriptions of a person’s identity, motive, or trading style.
What do LTH and STH actually measure?
Bitcoin accounting is built around unspent transaction outputs, or UTXOs. A transaction input spends a previous output, while a new output remains a UTXO until it is spent later. That structure gives analysts a measurable “age” for a coin output: the time since it last moved on-chain. The Bitcoin Developer Guide on transactions and UTXOs explains this underlying transaction model.
Glassnode’s widely used LTH/STH framework places an approximate dividing line around 155 days. Its research found that coins dormant for roughly that long become statistically less likely to be spent, while younger coins are more likely to circulate. The provider’s Long- and Short-Term Holder Supply methodology describes that threshold and its use in cohort analysis.
However, the exact implementation depends on the metric. For straightforward LTH-SOPR and STH-SOPR, Glassnode separates spent outputs at 155 days: at least 155 days for LTH-SOPR and younger than 155 days for STH-SOPR. For some entity-based supply metrics, its current API documentation describes a smoother classification using an entity’s average acquisition date, with a logistic weighting centered around 155 days rather than a hard cliff. That is why you should always read the definition of the exact series you are charting instead of assuming every “LTH” metric uses identical logic.
Can these metrics tell you who is buying or selling?
Not directly. They can show that older or younger coins moved, that estimated cohort supply changed, or that moved coins realized an on-chain profit or loss. They cannot prove that a particular person sold on an exchange.
This distinction matters because many economically important events happen off-chain. A centralized exchange can match buyers and sellers internally without moving Bitcoin on the blockchain. A custodian can also move coins between wallets without changing the beneficial owner. Conversely, one address can represent many users, while one user can control many addresses.
Entity-adjusted analytics try to reduce some of this noise by clustering addresses believed to belong to the same network entity and filtering transfers within that cluster. Glassnode’s entity-adjusted metrics documentation explicitly notes that this process depends on heuristics and statistical methods. The resulting data can be revised as clustering improves. In other words, entity-adjusted data is often more economically meaningful than raw address activity, but it is still an estimate.
Which LTH/STH metrics matter most before you act?
Metric
What it asks
Useful interpretation
Main trap
LTH/STH Supply
Where is the supply sitting by age cohort?
Shows whether more supply is becoming dormant or remaining in a younger, more active cohort.
Supply can change because coins simply age into a cohort; it does not require new buying.
LTH/STH SOPR
Were the coins that moved above or below their prior on-chain value?
Above 1 means the spent cohort moved at an aggregate profit; below 1 means an aggregate loss.
A “realized profit” on-chain does not prove a cash sale occurred.
LTH/STH MVRV
Is the cohort’s current market value above or below its realized value?
Helps estimate how much unrealized profit or loss is embedded in a cohort.
Realized value uses last movement as a cost-basis proxy, not a verified exchange purchase price.
Realized Cap / Realized Price
Where is the network or cohort’s value anchored by last movement?
Provides a cost-basis framework for comparing market price with the value at which coins last moved.
Self-transfers and custody movements can complicate the “cost basis” interpretation.
LTH Net Position Change
Is estimated long-term supply expanding or contracting over a rolling period?
Useful for detecting persistent accumulation/aging versus older-coin spending.
A single daily change is less informative than a multi-week trend.
Glassnode defines standard SOPR as the ratio between the value of spent outputs at the time they are spent and their value when those outputs were created. Its SOPR methodology treats values above 1 as aggregate realized profit and values below 1 as aggregate realized loss. The provider also publishes dedicated LTH-SOPR and STH-SOPR series.
How should you read short-term holder behavior?
STH metrics are most useful for understanding the part of the market whose coins moved relatively recently. This cohort often reacts more quickly to price changes because its cost basis is closer to the current cycle and its coins are statistically more likely to move again.
Start with STH-MVRV. Glassnode calculates STH-MVRV using only UTXOs younger than 155 days. A value above 1 means the cohort’s market value is above its realized value on aggregate; below 1 means the cohort is collectively below that proxy cost basis.
Then add STH-SOPR. Suppose STH-MVRV is below 1 and STH-SOPR is also below 1 for several sessions. The more defensible conclusion is not “the bottom is in.” It is that newer coin holders are underwater on average and some of the coins actually moving are crystallizing losses. If price simultaneously stops making new lows and loss realization begins to fade, that may become evidence of seller exhaustion—but it still needs confirmation from price structure, liquidity, and broader market conditions.
Conversely, STH-MVRV above 1 tells you short-term holders have aggregate unrealized profit, while STH-SOPR above 1 shows that the subset currently spending is realizing profit. That can coexist with a healthy uptrend. Profit-taking is not automatically bearish if demand is strong enough to absorb the supply.
How should you read long-term holder behavior?
LTH data becomes more useful when you distinguish coins that are still held from old coins that are being spent. Rising LTH supply often means more Bitcoin is aging into a low-spending cohort. It can be consistent with accumulation and reduced liquid supply, but the increase may happen simply because previously acquired coins cross the age threshold without moving.
Falling LTH supply indicates older supply is leaving the long-term cohort. That is stronger evidence of distribution when it is paired with elevated LTH spent volume, LTH-SOPR above 1, and—where reliable labeled data is available—flows toward exchanges or other liquid venues. Even then, “distribution” is a better description than “selling,” because on-chain movement alone does not reveal the final economic transaction.
Glassnode’s LTH-MVRV restricts MVRV to UTXOs at least 155 days old. Because older coins can have acquisition proxies far from the current market price, LTH-MVRV and LTH-SOPR can reach more extreme levels than their short-term equivalents. Treat those extremes as context about embedded profit and realized profit—not as fixed thresholds that must trigger a reversal.
Why is 155 days important, and why is it not a magic number?
The 155-day boundary is a statistical heuristic, not a rule built into Bitcoin. It emerged from historical analysis of spending probability: the longer a coin remains dormant, the less likely it becomes to move again, and the curve becomes meaningfully different around a several-month horizon. Glassnode standardized roughly 155 days for its long- and short-term framework.
That threshold is useful because it creates consistent cohorts, but it should not be interpreted as “a person becomes a long-term investor on day 155.” Modern supply implementations may smooth the transition around the boundary, and different analytics providers can use different cohort definitions. When comparing dashboards, verify whether you are looking at raw UTXO age, entity-adjusted age, an average acquisition date, or a provider-specific weighting method.
What combinations are more useful than a single signal?
1. LTH supply rising while STH supply falls
This usually means a larger share of supply is aging into dormancy and a smaller share remains in the younger cohort. It can support an accumulation narrative, particularly after a bear-market drawdown. But it is not necessarily a near-term price signal; coins can age while price remains weak or sideways.
2. LTH supply falling while LTH-SOPR is strongly above 1
This combination suggests older coins are moving and the moved supply has substantial aggregate profit relative to its previous on-chain value. It is consistent with long-term holders distributing into market strength. The bearishness depends on whether new demand can absorb that supply.
3. STH-MVRV below 1 and STH-SOPR below 1
This points to stress among newer holders: their aggregate market value is below realized value, and the coins being spent are realizing losses. It can accompany capitulation. A trader should still ask whether selling pressure is slowing before treating it as a reversal setup.
4. STH-MVRV back above 1 after a recovery
This can indicate that the short-term cohort has moved back into aggregate unrealized profit. If STH-SOPR also holds around or above break-even during pullbacks, that may suggest buyers are defending recent cost bases. The signal is more useful as a market-structure clue than as an isolated entry trigger.
What can distort an on-chain conclusion?
Exchange activity can be invisible on-chain. Trades inside a centralized exchange can change ownership without any Bitcoin transaction.
Wallet maintenance can look like economic activity. Consolidation, change outputs, custody reorganization, and security migrations can move UTXOs without representing a market decision.
Address counts are not user counts. One entity can control many addresses, and one custodian address can represent many customers.
Realized “cost basis” is a proxy. Realized capitalization values UTXOs at the price when they last moved. Glassnode’s Realized Capitalization documentation explains that construction. A last-moved price is not always the holder’s true purchase price.
Entity-adjusted history can change. Better clustering and newly identified wallets can revise recent or historical points. Glassnode documents this mutability and offers point-in-time metrics for cases such as backtesting where it matters what data was known at the time.
A practical decision checklist
Before acting on an LTH/STH chart, answer these questions in order:
What exactly is being measured? Held supply, spent supply, profitability, realized value, or transfer flow?
How is the cohort defined? Hard 155-day UTXO age, smoothed entity age, or another provider-specific method?
Is the metric raw or entity-adjusted? Raw UTXO activity is transparent but noisier; entity-adjusted data is more interpretive and heuristic.
Is the move persistent? Prefer multi-day or multi-week trends over one-day spikes unless you can explain the event.
Does another metric confirm it? Pair supply with spending and profitability. For example, falling LTH supply becomes more informative when LTH-SOPR and old-coin spent volume also rise.
Does price behavior agree? On-chain data is context. Price, liquidity, derivatives positioning, macro conditions, and market structure can determine whether a cohort shift matters now or later.
Bottom line
LTH/STH analysis is most powerful when it answers a sequence rather than a single question. First ask where the supply is aging. Then ask which cohort is actually spending. Finally ask whether those spent coins are moving at a profit or loss relative to their prior on-chain value.
The 155-day framework gives analysts a consistent way to separate older, statistically less-active supply from younger, more-active supply, but it is a model—not a natural law and not a direct view into investor intent. Use LTH/STH Supply for dormancy and cohort balance, SOPR for realized spending profitability, and MVRV or realized-price measures for embedded unrealized profit or loss. The strongest conclusions come when several of those dimensions agree.
Methodology note: Definitions and source documentation in this article were checked against the Bitcoin Developer Guide and Glassnode documentation on September 14, 2026. On-chain analytics are estimates derived from public blockchain activity and provider-specific heuristics. This article is educational and is not investment advice.