Forex Session Overlap in Local Time: The 2026 DST Shift
See how U.S. and U.K. daylight saving dates shift the London–New York forex overlap, with 2026 local-time examples and a practical conversion method.
Two investments can rise and fall in step with the market and still expose an investor to very different swings. The reason is that correlation measures how consistently returns move together, while beta measures how sensitive an asset’s returns are to a chosen benchmark. One describes co-movement; the other describes scale-adjusted market exposure.
This distinction is useful when comparing stocks, funds, or asset classes. A pair of assets can have the same correlation with a benchmark but different volatility and different beta. Neither measure captures every kind of risk, and both are estimates based on a selected period of historical returns.
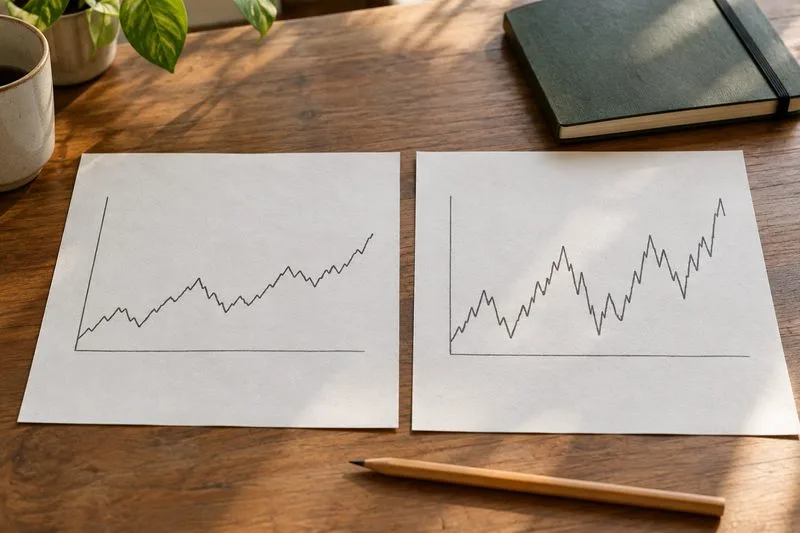
Correlation is a standardized measure of how two sets of returns move together. It ranges from −1 to +1. A positive value means the returns have tended to move in the same direction; a negative value means they have tended to move in opposite directions; a value near zero means little linear co-movement in the measured sample.
Correlation does not measure how large either asset’s gains or losses are. The calculation standardizes each return series by its own variability. If one asset’s daily returns are usually larger than another’s but their ups and downs arrive at similar times, the two assets can still have the same correlation with a benchmark.
Useful action: When judging whether a holding may diversify a portfolio, examine its correlation with the portfolio or benchmark over a relevant period, then also check the asset’s own volatility and how it behaves in stressful markets. A low historical correlation alone does not establish that an investment is safe.
Beta is the slope of an asset’s returns relative to a benchmark’s returns in a statistical model. In its standard form:
Beta = Covariance(asset, benchmark) ÷ Variance(benchmark)
The same relationship can be written as:
Beta = Correlation(asset, benchmark) × (Asset standard deviation ÷ Benchmark standard deviation)
So beta depends on both correlation and relative volatility. A beta of 1 indicates that, in the fitted sample, the asset’s returns had roughly the same sensitivity to benchmark movements as the benchmark had to itself. A beta above 1 indicates greater estimated sensitivity; a beta below 1 indicates lower estimated sensitivity. A negative beta means the fitted relationship has been inverse over that sample.
William F. Sharpe’s 1964 paper on capital asset prices distinguishes an asset’s systematic response to a chosen market combination from the remaining, asset-specific variation. In modern investing, beta is commonly used as a proxy for benchmark-related or systematic sensitivity. It is not a complete measure of risk. The original paper is available through The Journal of Finance.
Illustrative example, not historical market data: Assume a benchmark has annualized volatility of 15%. Asset A has annualized volatility of 15% and correlation of 0.80 with the benchmark. Its beta is 0.80 × (15% ÷ 15%), or 0.80. Asset B also has correlation of 0.80, but its annualized volatility is 30%. Its beta is 0.80 × (30% ÷ 15%), or 1.60.
Both assets have the same measured degree of co-movement with the benchmark, but Asset B has twice the estimated beta. In a simple interpretation of those fitted slopes, if the benchmark rises 1%, Asset A’s estimated response is about 0.8%, while Asset B’s is about 1.6%. Those are averages implied by a model, not predictions that either asset will move by those exact amounts on the next trading day.
The example also shows why “they move together” is not enough information to compare risk. Correlation describes the pattern after scaling each return series; beta restores information about how large the asset’s typical moves are relative to the benchmark.
It means they had a similar standardized linear relationship with the comparison series in the chosen sample. It says nothing by itself about how volatile each asset was. Check each asset’s standard deviation, beta, and loss history alongside correlation.
Beta is a fitted sensitivity, not a fixed daily multiplier. Actual returns can differ because of company news, sector exposure, currency moves, or random variation around the regression line. Review the estimation period and compare the beta with the asset’s realized returns; do not treat it as a promise.
Beta isolates movement associated with a benchmark. It does not summarize all company-specific, liquidity, concentration, gap, or operational risks. FINRA’s investor guidance distinguishes stock volatility from other stock risks and notes the special risks associated with growth companies and financing costs. For a position-level assessment, also examine total volatility, drawdowns, liquidity, leverage, and the possibility of permanent loss.
Neither statistic guarantees protection from losses. An asset can have low estimated market sensitivity but still face severe issuer-specific or liquidity problems. And correlations calculated from past returns can change when market conditions change. Treat both figures as historical descriptions, not assurances about the future.
| Question | Measure to start with | What it leaves out |
|---|---|---|
| How closely has this asset moved with my portfolio or benchmark? | Correlation | Size of the asset’s own moves and losses |
| How sensitive have its returns been to benchmark returns? | Beta | Risks unrelated to the chosen benchmark |
| How variable have the asset’s returns been overall? | Standard deviation or realized volatility | Whether losses are more important than gains; volatility treats both directions alike |
| How might a large loss affect my plan? | Drawdown, scenario analysis, liquidity and position size | No single past statistic can map every future shock |
Correlation is especially relevant when considering diversification because portfolio volatility depends on each holding’s volatility, the correlation between holdings, and their portfolio weights. A CFA Institute educational example lays out this two-asset variance relationship and demonstrates how changing correlation changes portfolio volatility. Review the CFA Institute portfolio-variance example and calculate risk using the actual weights you expect to hold, rather than looking at a pairwise correlation in isolation.
Beta is always relative to something. A stock’s beta against a broad U.S. equity index may differ from its beta against a sector index or a global index. The result also depends on the return frequency and sample window: daily, weekly, or monthly returns can produce different estimates, and a short period may be dominated by a few unusual observations.
Correlation is also sample-dependent, although it does not require choosing a market benchmark when comparing two assets directly. The analyst still has to choose the assets, currency, return frequency, and time window. Compare like with like: use adjusted total returns where appropriate, align observation dates, and make the benchmark match the question. If the portfolio is international or includes bonds and commodities, a single domestic stock index may not represent all of its common risk.
Useful action: Before relying on a reported beta, identify the benchmark, the observation frequency, the sample dates, and whether the figure uses adjusted returns. If those details are unavailable, treat the number as a rough reference rather than a precise risk forecast.
The core distinction is simple: two assets may move together to a similar degree and still carry different market exposure because their return magnitudes differ. Correlation helps explain how investments interact. Beta helps explain how strongly an asset has responded to a benchmark. For a fuller risk picture, use both with volatility, portfolio weights, and an honest review of what the statistics cannot tell you.
Source note: The definitions and equations in this article describe standard historical-return statistics. Estimates vary by benchmark and sample choices; they do not predict future performance.
See how U.S. and U.K. daylight saving dates shift the London–New York forex overlap, with 2026 local-time examples and a practical conversion method.
See how the 30-day wash-sale window, partial share matches, basis adjustments, Form 8949, broker reporting, and section 475(f) affect active traders.
Learn why a single stock order can be partially filled at different prices and times, how liquidity and queue priority drive fills, and what to check before trading.
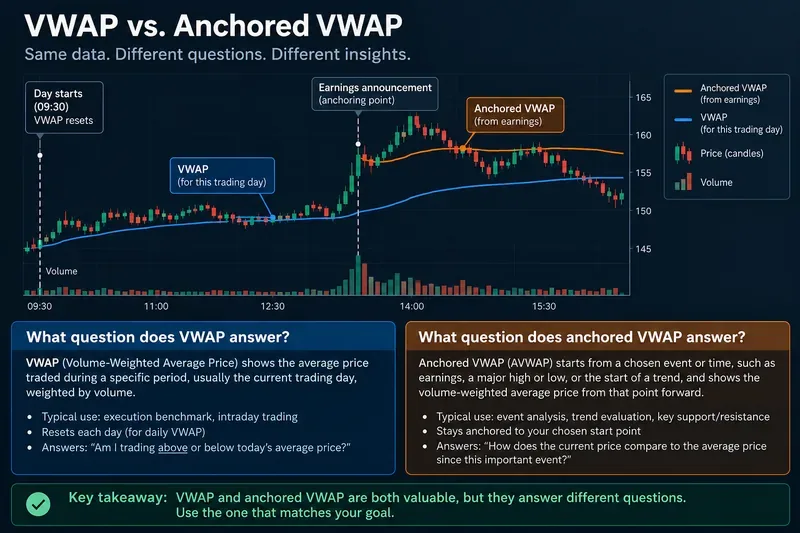
VWAP measures the volume-weighted average for a defined session; anchored VWAP starts from a chosen event. Learn when each benchmark is the better fit.
Compare market and limit orders in fast markets. Learn how fill likelihood, slippage, price limits, and queue priority affect execution—and what to check before trading.
Understand how volume profile defines the value area, VAH, VAL, and POC, what these levels can reveal, and why settings and data sources change the reading.
Learn how correlation and beta differ, why assets with the same correlation can have different market sensitivity, and what each measure leaves out.
Learn what FX forward points are, how interest-rate differentials and cross-currency basis shape them, and why a forward rate is a hedge price—not a spot forecast.
Learn how to calculate currency carry trade returns by combining interest income, exchange-rate movement, rollover financing, spreads, and commissions in a worked example.
Learn how nominal and real Treasury yields differ, why real yields often matter more for gold, and how both rates affect growth stock valuations.