Forex Session Overlap in Local Time: The 2026 DST Shift
See how U.S. and U.K. daylight saving dates shift the London–New York forex overlap, with 2026 local-time examples and a practical conversion method.
Frequent trading does not, by itself, switch off the federal wash-sale rule. If you trade securities in a taxable account and do not have a valid mark-to-market election under Internal Revenue Code section 475(f), a loss can be disallowed when you acquire substantially identical stock or securities during the 30-day period before or after the loss sale. The disallowed amount is generally added to the replacement shares’ tax basis, postponing the deduction rather than erasing it. An acquisition in an IRA or Roth IRA is a special case: the loss is disallowed, but the IRA’s basis is not increased.
Illustrative hypothetical: Jordan is an active stock trader using a regular taxable brokerage account. Jordan buys 100 shares of Northstar Labs at $100 per share, sells all 100 at $88, then buys 40 shares of the same company at $92 ten days later. These invented dates and prices are only an example; they are not a real trade or tax result. The records show a $1,200 realized loss on the sale, but the later purchase falls inside the wash-sale window.
The IRS describes the rule in Publication 550, Investment Income and Expenses. This article reflects IRS materials available September 30, 2026, including the 2025 publication and 2025 tax-form instructions. Individual facts, account types, and securities can change the result.
For a loss on a stock or security, check purchases and other acquisitions of substantially identical securities during the 30 days before and the 30 days after the sale. The sale date sits between those two periods. The rule can also cover a fully taxable exchange, acquiring a contract or option to buy substantially identical securities, and purchases made for your IRA or Roth IRA. A spouse’s purchase or a purchase by a corporation you control can also trigger a wash sale under Publication 550.
That means a trader who sells at a loss and buys back the same stock the next morning should not assume the loss is currently deductible. It also means a trader must look backward: a purchase made shortly before a loss sale can count. Keep the surrounding transactions, not just the sell order, in the record.
“Substantially identical” is a facts-and-circumstances standard. The same company’s common stock is the clearest case. Whether two different funds, options, or other instruments are substantially identical may require tax analysis; the ticker symbol alone does not settle every comparison. The IRS materials do not provide a universal ETF substitution chart. When the answer is uncertain, preserve the instrument descriptions and get advice from a qualified tax professional rather than treating correlation as a definitive test.
Assume Jordan’s initial 100 shares cost $10,000 total and the sale proceeds are $8,800 before any transaction costs. The realized loss is $1,200, or $12 per share. Ten days after the sale, Jordan buys 40 substantially identical shares for $3,680. The matching 40 shares cause $480 of the original loss to be disallowed for now: 40 replacement shares multiplied by $12 loss per share. The remaining $720 loss relates to the 60 unmatched shares, assuming no other acquisitions fall in the relevant window.
| Record entry | Illustrative detail | Tax tracking |
|---|---|---|
| Original purchase | 100 shares at $100; total basis $10,000 | Save confirmation and acquisition date |
| Loss sale | 100 shares at $88; proceeds $8,800; realized loss $1,200 | Review the 30 days before and after |
| Replacement purchase | 40 shares at $92, ten days after sale; cost $3,680 | Match 40 shares; defer $480 |
| Adjusted replacement basis | $3,680 cost plus $480 deferred loss = $4,160 | Adjusted basis is $104 per share |
In this simplified example, the $480 disallowed loss is added to the basis of the 40 replacement shares, and the holding period of those shares includes the holding period of the shares sold. If Jordan later sells the 40 replacement shares for $110 each, with no new wash-sale transaction around that later sale, the adjusted basis of $4,160 produces a $240 gain. The earlier sale’s reportable loss is reduced by the $480 adjustment, leaving $720 of loss on that sale. Together, the two trades show a net $480 loss, matching the simplified economic result. Fees, partial lots, additional trades, and other tax facts can alter the arithmetic.
Publication 550 explains the basis adjustment and holding-period carryover. A wash sale therefore often changes when a loss is recognized. The IRA/Roth IRA rule is different: the loss is disallowed without adding it to the IRA’s basis, as described in Revenue Ruling 2008-5.
For Jordan, the ledger should link the August loss sale to the 40 replacement shares, preserve the $480 basis addition, and leave an explanation for the 60 shares with no match. Keeping this link matters if the replacement shares are sold in a later tax year; otherwise a postponed loss can be missed or counted twice.
Form 1099-B can report a wash-sale adjustment in box 1g for covered securities when the broker’s reporting conditions are met. IRS broker instructions generally require reporting when both transactions involve covered securities with the same CUSIP in the same account. A broker may report some situations beyond that minimum, but traders remain responsible for accurate tax reporting. Cross-account trades, a spouse’s account, an IRA, options, and securities that do not share the same identifier can require review beyond the form.
Do not treat a blank wash-sale box as proof that no wash sale occurred. The IRS Instructions for Form 1099-B describe the broker’s reporting rules, while the Instructions for Schedule D state that the taxpayer must account for wash-sale losses even if a broker did not report them. Compare broker totals with your own trade and household records before filing.
For a taxpayer reporting capital transactions, the Instructions for Form 8949 direct filers to enter code “W” in column (f) and the nondeductible loss as a positive adjustment in column (g). That positive adjustment reduces the deductible loss or increases the reported gain. The transaction is reported in the appropriate short-term or long-term section, and Form 8949 totals generally flow to Schedule D.
In Jordan’s simplified numbers, if the broker statement reports the $1,200 loss and $480 wash-sale amount, the Form 8949 adjustment reconciles the transaction so that only $720 is recognized currently. The $480 is carried into basis of the replacement shares, unless the replacement purchase was in an IRA or Roth IRA. Use the current form instructions for the tax year being filed; column labels and reporting procedures can change.
Potentially. IRS guidance distinguishes a securities trader who has made a valid, timely section 475(f) mark-to-market election from a person who merely trades frequently. The IRS says traders without that election generally report security sales as capital gains and losses, and wash-sale rules continue to apply. For securities held in the trading business by a trader with an effective mark-to-market election, the wash-sale rule does not apply; gains and losses are generally reported as ordinary items on Form 4797. Investment positions kept outside the trading business are treated separately.
Election timing is strict. The IRS says the election is generally due by the due date, without extensions, of the return for the year before the election year. Trader status also depends on the nature and continuity of the activity, not a self-selected label. Read IRS Topic No. 429 and the Form 4797 instructions before relying on this treatment. A late or invalid election does not convert ordinary active trading into mark-to-market treatment.
Official references: IRS Publication 550; Instructions for Form 8949; Instructions for Schedule D; Instructions for Form 1099-B; Instructions for Form 4797; and IRS Topic No. 429.
This educational overview is not individualized tax advice. Ask a tax professional to review uncertain substantially identical securities, IRA interactions, trader status, or section 475(f) elections.
See how U.S. and U.K. daylight saving dates shift the London–New York forex overlap, with 2026 local-time examples and a practical conversion method.
See how the 30-day wash-sale window, partial share matches, basis adjustments, Form 8949, broker reporting, and section 475(f) affect active traders.
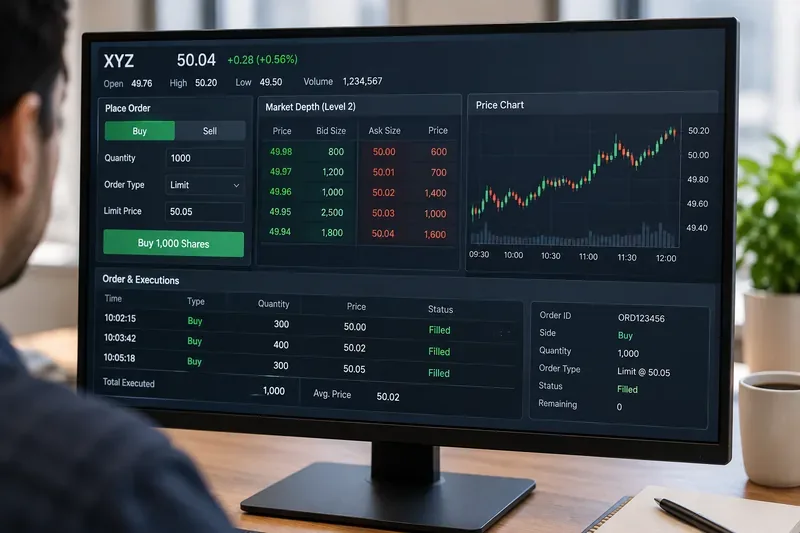
Learn why a single stock order can be partially filled at different prices and times, how liquidity and queue priority drive fills, and what to check before trading.
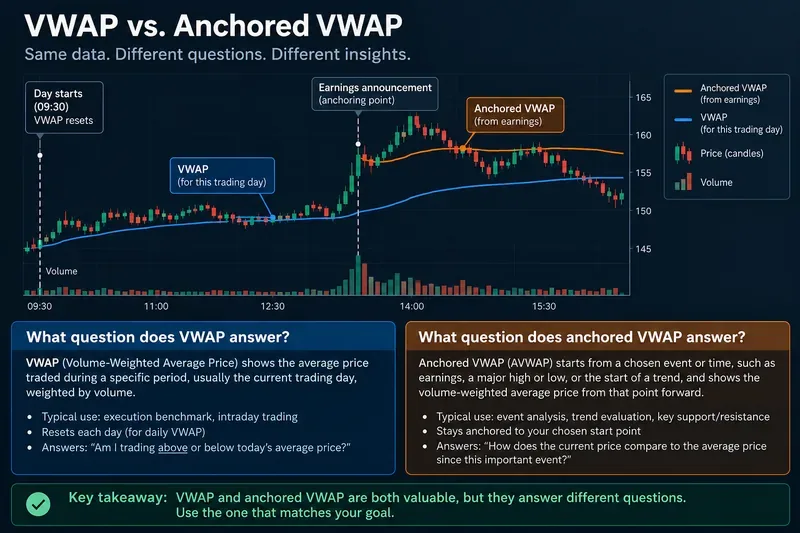
VWAP measures the volume-weighted average for a defined session; anchored VWAP starts from a chosen event. Learn when each benchmark is the better fit.
Compare market and limit orders in fast markets. Learn how fill likelihood, slippage, price limits, and queue priority affect execution—and what to check before trading.
Understand how volume profile defines the value area, VAH, VAL, and POC, what these levels can reveal, and why settings and data sources change the reading.
Learn how correlation and beta differ, why assets with the same correlation can have different market sensitivity, and what each measure leaves out.
Learn what FX forward points are, how interest-rate differentials and cross-currency basis shape them, and why a forward rate is a hedge price—not a spot forecast.
Learn how to calculate currency carry trade returns by combining interest income, exchange-rate movement, rollover financing, spreads, and commissions in a worked example.
Learn how nominal and real Treasury yields differ, why real yields often matter more for gold, and how both rates affect growth stock valuations.